WASHINGTON — In an evolving economic landscape marked by the rise of the freelance economy, contract work, and entrepreneurial ventures, millions of households face a reality distinct from the traditional 9-to-5 salaried structure: the irregular income. While self-employment offers flexibility and autonomy, it introduces a unique psychological and logistical challenge—how to build a secure financial life when the amount deposited into your bank account fluctuates wildly from month to month.
For years, many self-employed individuals and small-business owners avoided household budgeting entirely, assuming that planning was exclusively for those with steady, predictable paychecks. However, financial experts and seasoned practitioners of variable-income budgeting increasingly argue the opposite: tracking, planning, and forecasting are exponentially more critical when your cash flow is unpredictable. Without a reliable framework, households with fluctuating revenues run a severe risk of overspending during high-earning months, leaving them vulnerable when lean periods inevitably strike.
The Core Challenge: Shifting From Fear to Financial Control
For many, the hesitation to budget stems from a fear of restriction. When income is volatile, looking closely at expenses can feel like confronting an impending shortage. However, changing one’s perspective is the first step toward lasting financial stability.
Rather than acting as a constraint, a well-structured budget serves as a strategic roadmap. It answers critical questions: What are our baseline survival costs? How much can we comfortably afford on fixed commitments like housing? And how do we handle unexpected expenses without plunging into high-interest debt?
To build a resilient financial foundation on a variable income, experts recommend a four-pillar approach designed to smooth out the financial roller coaster.
1. Baseline Budgeting: Designing for the Leanest Month
The foundational mistake many variable-income earners make is basing their lifestyle and monthly spending targets on their best months—or worse, on an optimistic average. When a high-earning month is followed by a slow quarter, this approach quickly leads to a financial shortfall.

Conservative Spending Targets
The primary rule of variable income management is to build your core budget around a conservative, lower-end income estimate. By anchoring your baseline lifestyle expenses—housing, utilities, groceries, and insurance—to a month where earnings are historically low, you ensure that your fundamental financial obligations are always met.
- Fixed Commitments: Major long-term decisions, such as mortgage payments, auto loans, and recurring subscription services, should be evaluated against your lower-end income threshold.
- Preventing Lifestyle Creep: Adopting a conservative baseline prevents the dangerous habit of inflating your standard of living during prosperous periods, ensuring long-term resilience.
2. Building the Buffer: The Imperative of the Emergency Fund
Even the most carefully crafted conservative budget cannot completely insulate a household from sudden economic shifts, slow business cycles, or unexpected emergencies. This makes a robust emergency fund or "buffer fund" an absolute necessity for irregular earners.
Automating Savings
Building a buffer requires consistency, but human psychology often works against us. When extra cash sits in a primary checking account, the temptation to spend it can be overwhelming. To combat this, financial planners recommend setting up automated weekly or monthly transfers into a separate savings vehicle.
"If we had to make the transfer manually, there would always be a reason why I felt more comfortable leaving the money in checking," notes financial organization advocate Abby Lawson. "When it’s automatic, you don’t even have to think about it."
Determining the Right Emergency Fund Size
Financial benchmarks for emergency savings vary depending on individual risk tolerance and income volatility:
- The Starting Goal: For those just beginning their savings journey, a modest initial target of $1,000 provides a cushion against minor mishaps like car repairs or medical copays.
- The One-Month Benchmark: The next milestone is accumulating enough cash to cover a full month’s worth of essential expenses.
- The 3- to 6-Month Standard: Standard financial advice recommends holding three to six months of essential living expenses. However, for those with highly volatile business models, expanding this buffer to cover six months to a full year of expenses is often necessary for peace of mind.
3. The Surplus Strategy: Maximizing High-Income Months
What happens when a business experiences an unexpectedly profitable month, bringing in revenue well above the conservative baseline? Rather than letting excess cash dissolve into impulse purchases, successful budgeters establish a predetermined hierarchy of financial priorities.

Creating an Ordered Priority List
Couples and individuals should outline a prioritized wish list for surplus funds before the money arrives. When extra cash materializes, it can be systematically allocated toward:
- Reinforcing the Buffer: Topping off emergency reserves if they were depleted during previous lean months.
- Debt Reduction: Accelerating payments on high-interest consumer debt or student loans.
- Sinking Funds for Predictable Expenses: Setting aside money for annual obligations, such as property taxes, insurance premiums, tuition, or holiday spending.
- Long-Term Wealth Building: Maximizing retirement contributions, funding college savings accounts (529 plans), or investing in taxable brokerage portfolios.
Striking a Balance: The Role of Discretionary Spending
A common pitfall in budgeting is radical austerity. When individuals completely eliminate hobbies, entertainment, and fun splurges, they often experience "budget fatigue." This exhaustion frequently leads to emotional overspending, where the individual abandons the budget entirely out of frustration. An effective variable budget must intentionally carve out room for discretionary spending to ensure long-term sustainability.
4. Agility and Adaptation: The Evolving Budget
A budget is not a static document carved in stone; it is a living financial tool that must adapt to changing realities.

Tracking Patterns and Adjusting Categories
Month-over-month tracking reveals behavioral patterns and seasonal spending shifts.
- Reallocating Funds: If data shows that a specific category consistently underspends, those funds can be reallocated to higher-priority goals.
- Realism Over Frustration: If a category consistently runs over budget despite best efforts, the budgeted amount should be adjusted to reflect realistic costs rather than inviting continuous frustration.
Structural Adjustments
If tracking reveals that baseline income is persistently failing to cover essential expenses—even after rigorous cutting—households must take proactive measures. This may involve negotiating a salary increase, developing a side hustle to bridge the earnings gap, or making difficult decisions regarding major overhead expenses. Budgeting provides the empirical data required to make these proactive interventions before a crisis hits.
Chronology of Financial Adaptation for Variable Earners
| Phase | Milestone / Action | Primary Objective |
|---|---|---|
| Phase 1: Assessment | Audit past 12 months of income and expenses. | Determine historical low, average, and high income months. |
| Phase 2: Baseline Setup | Build a monthly spending plan scaled to the lowest income month. | Secure essential living standards against slow periods. |
| Phase 3: Automation | Establish automatic transfers to a dedicated emergency buffer. | Remove human friction from the saving process; build a 3-to-6-month safety net. |
| Phase 4: Surplus Planning | Create an ordered wish list for earnings above the baseline. | Intentionally direct windfalls toward debt paydown, investing, and sinking funds. |
| Phase 5: Review & Refine | Conduct monthly check-ins using tracking tools or spreadsheets. | Adjust category limits based on real-world spending data and changing lifestyle needs. |
Supporting Data and Digital Tools
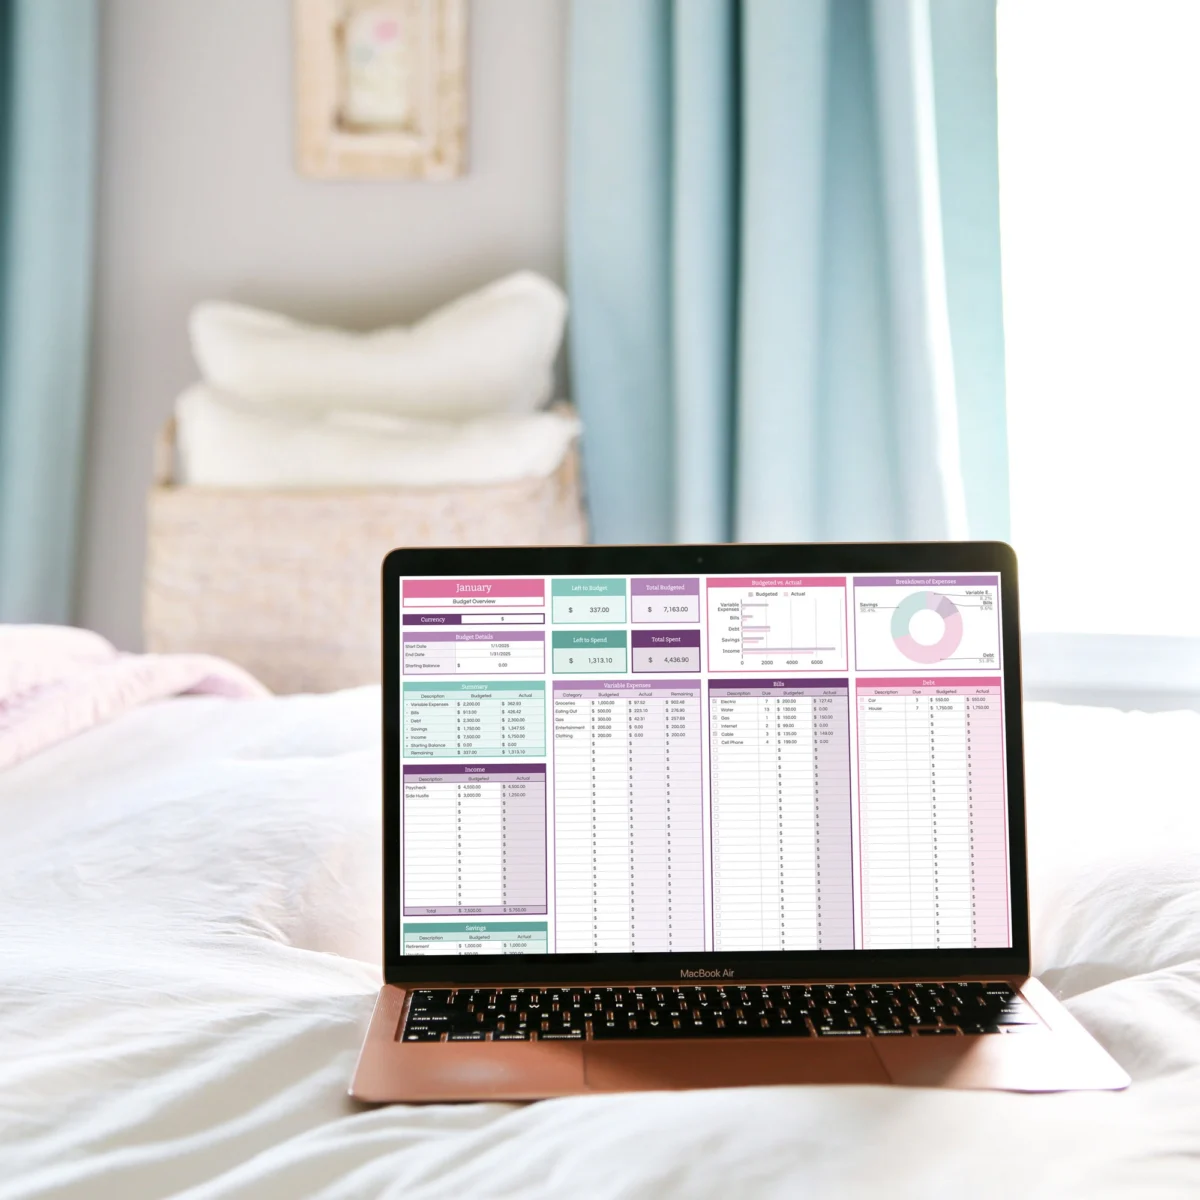
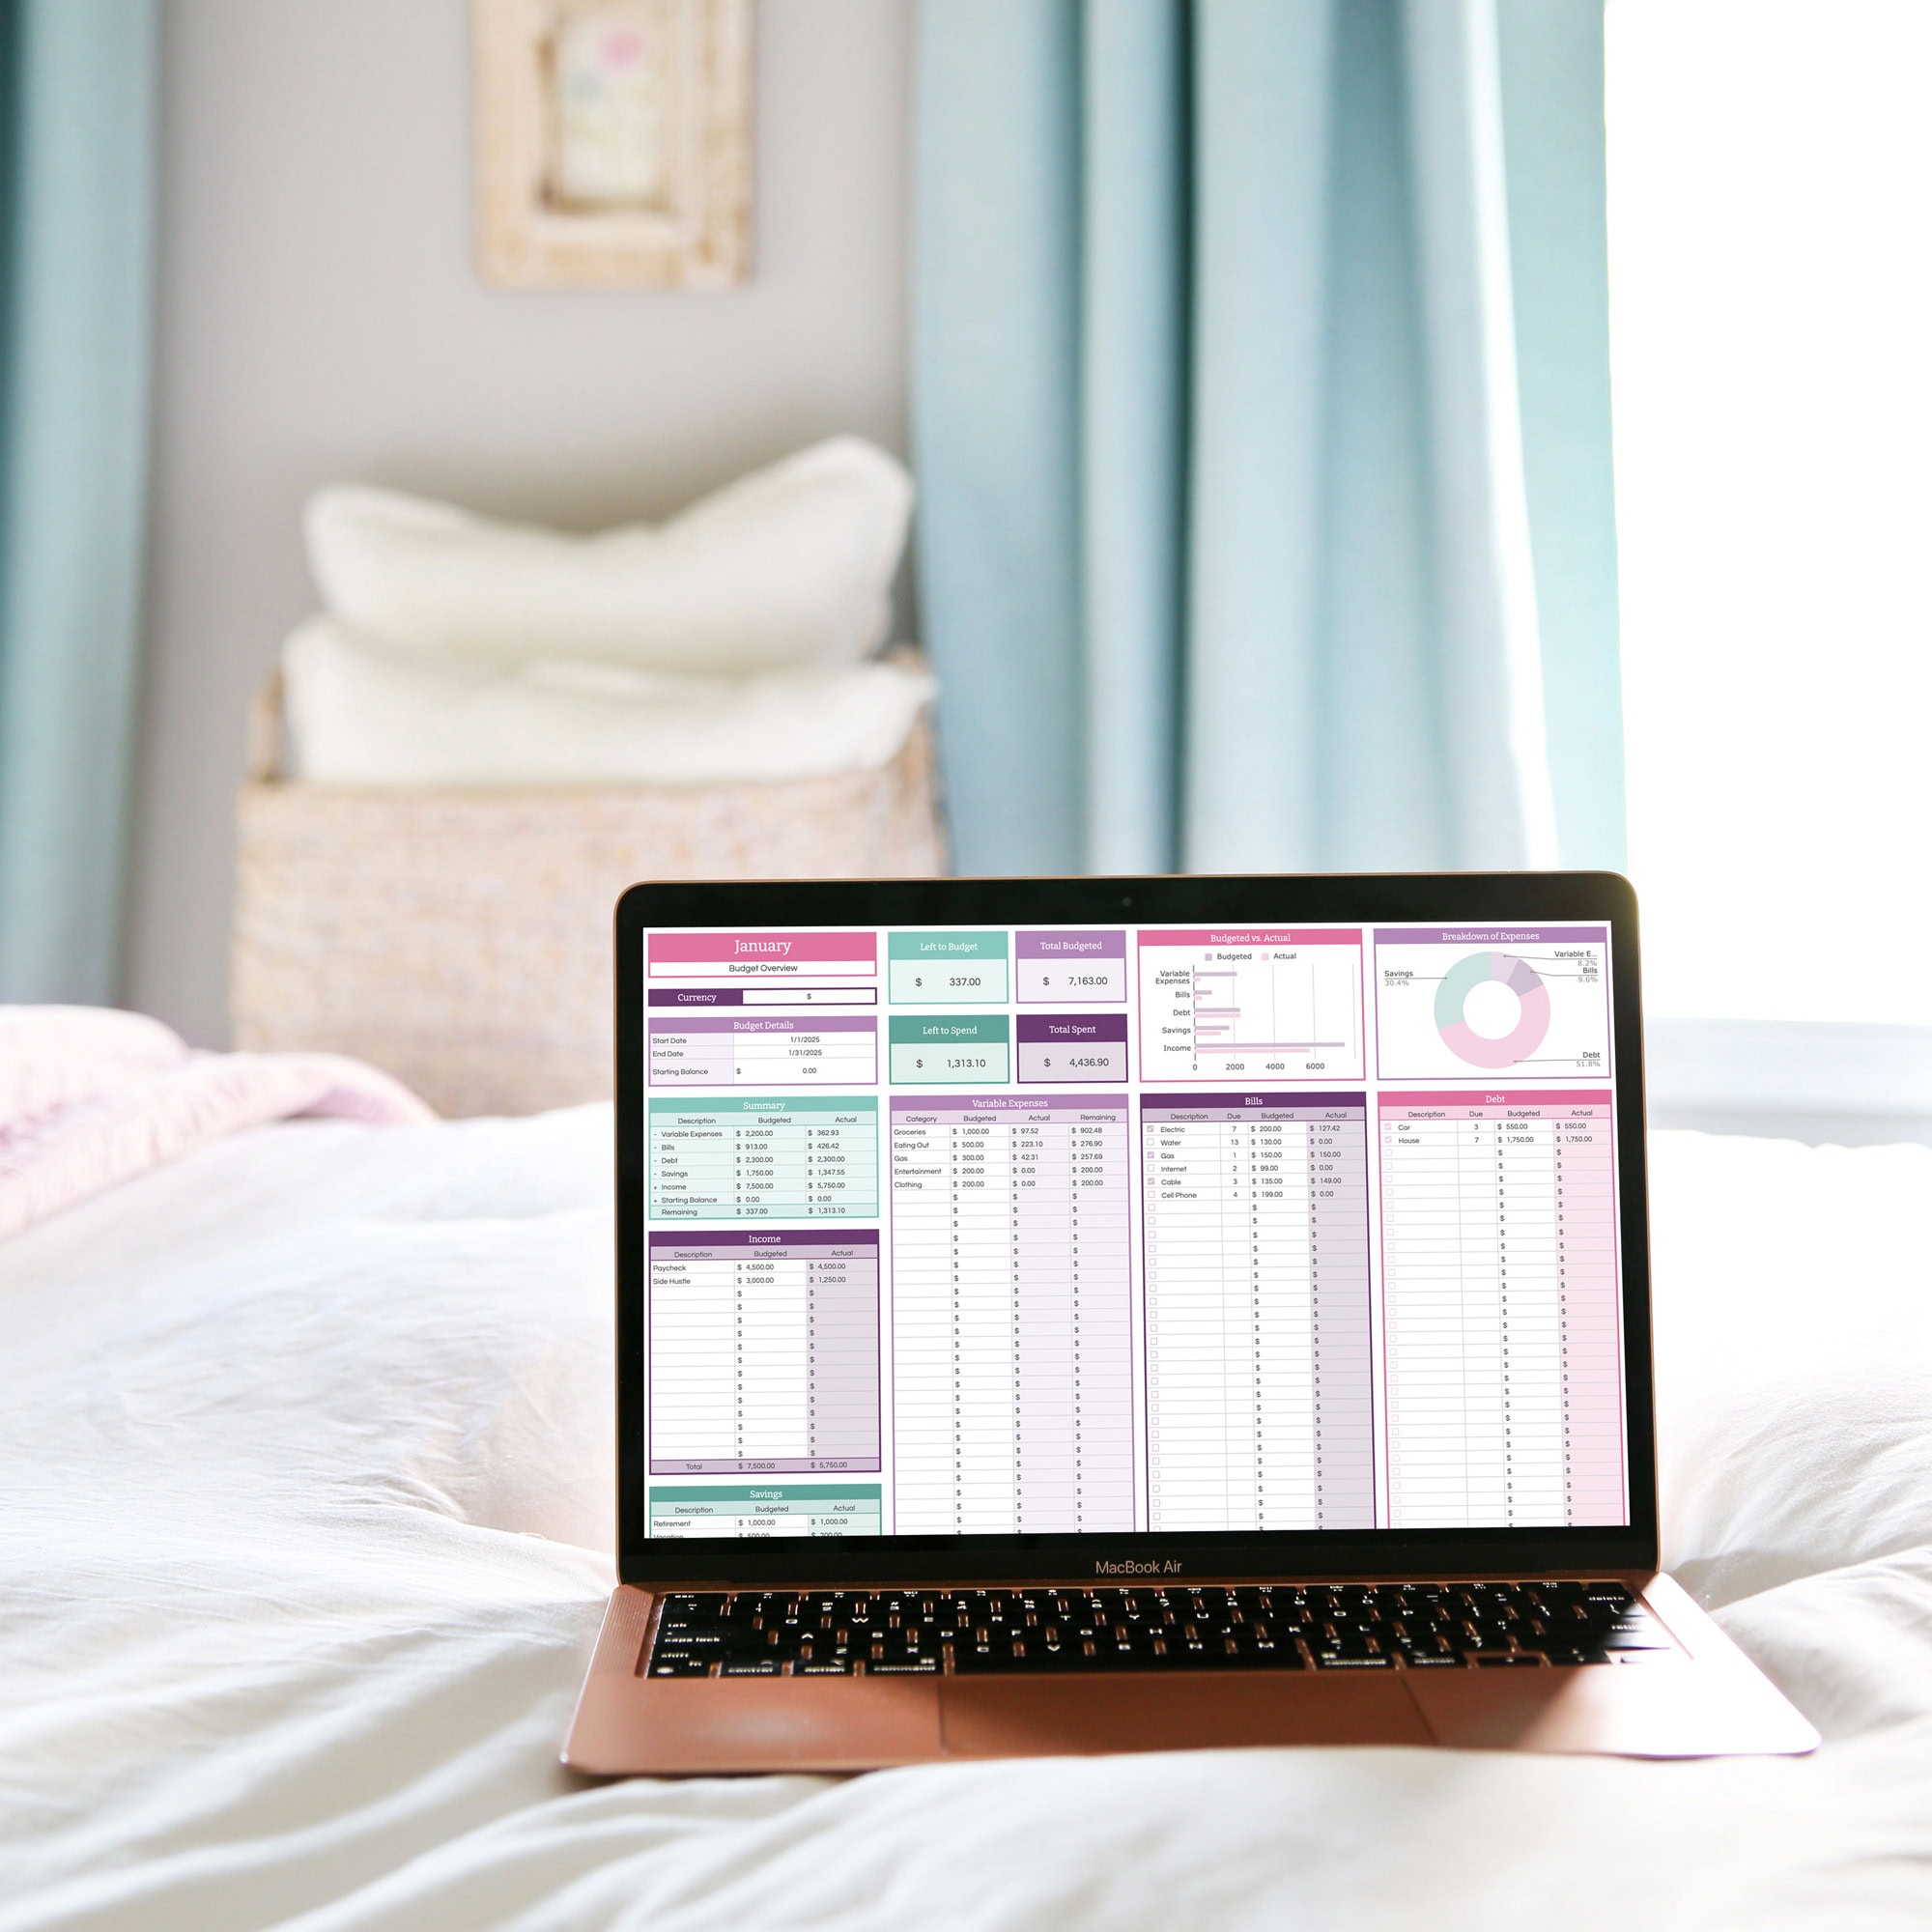
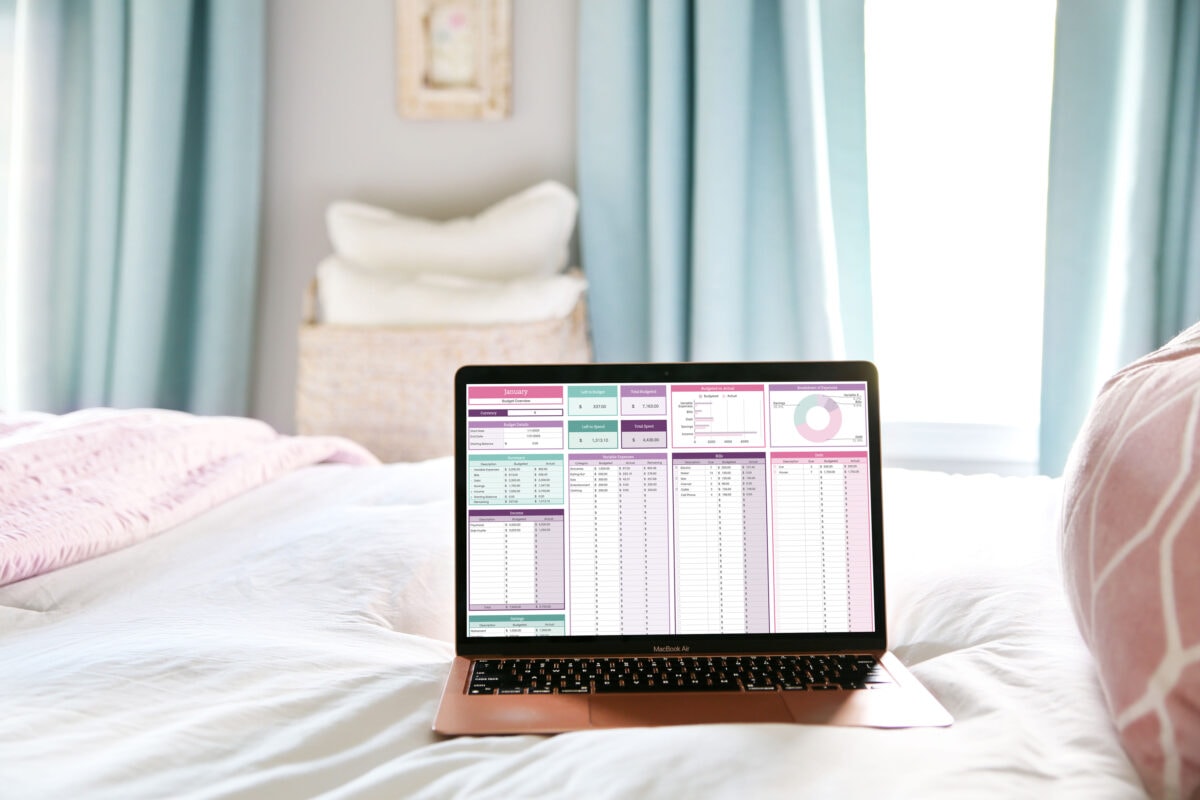
The transition from financial anxiety to proactive management is heavily supported by modern organizational tools. While pen-and-paper ledgers have historic utility, digital spreadsheets have become the standard for modern household accounting.

Financial analysts note that the simple act of regular tracking—often referred to as maintaining a "money routine"—naturally curbs impulsive purchasing behavior. By utilizing structured spreadsheets that automatically calculate totals, categorize transactions, and forecast annual trends, beginners can demystify their cash flow without requiring an advanced degree in accounting.
Implications for the Modern Workforce
As the percentage of workers engaged in freelance, gig, and entrepreneurial work continues to expand globally, the cultural perception of financial planning must shift. Traditional financial advice has long prioritized the stability of the W-2 salary, often leaving non-traditional workers feeling excluded from mainstream wealth-building strategies.
Experts emphasize that mastering an irregular income does more than just prevent overdraft fees; it builds psychological resilience. When individuals take charge of their cash flow, knowing precisely what they can afford and where they can adjust, money transforms from a source of chronic stress into a tool for empowerment.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute personalized financial, legal, or professional advice. Readers should consult with a certified financial planner or qualified professional before making major financial decisions.