The narrative surrounding retirement downsizing has become a cultural script: the children arrive for Thanksgiving, look at the oversized house, and gently suggest that it is time to move to something more "manageable." The financial advisor concurs, pointing to the mountain of equity trapped in the walls. The neighbor suggests a golf-course condo, citing the freedom of a lock-and-leave lifestyle.
It is a persuasive, well-meaning, and often dangerous piece of advice. While downsizing is frequently treated as an obvious financial windfall, it is rarely the cash-generating maneuver that families imagine. In reality, downsizing is a massive, complex transaction—a high-stakes capital reallocation that, if miscalculated, can drain your retirement accounts rather than fortify them. Before putting a "For Sale" sign in the yard, retirees must move beyond the emotional appeal of "right-sizing" and perform the cold, hard arithmetic of a break-even analysis.
Main Facts: The Hidden Costs of Transition
The fundamental flaw in the standard downsizing pitch is the conflation of the "sticker gap" with "liquid cash." If you sell a home for $500,000 and buy one for $350,000, the assumption is that you have unlocked $150,000. This is almost never true.
The process of moving is a consumer-heavy, fee-laden event. When you sell, you pay agent commissions (historically 3% to 8%, though now subject to individual negotiation following recent regulatory shifts), transfer taxes, and closing costs. When you buy, you pay title insurance, inspection fees, and mortgage origination costs. Then, there is the physical move itself—professional packing, moving crews, and the inevitable "setup" costs. These include new window treatments for different-sized windows, custom closet organizers, and repairs that the new home inspection might have missed.
In many cases, 10% to 20% of your total home equity can evaporate into the transaction costs of the move itself. For retirees who own their homes outright—a demographic that includes roughly 60% of homeowners aged 65 to 79—the monthly savings on utilities and taxes in a smaller home are often marginal. If your current house is already paid off, you have already reached the "floor" of housing costs. Replacing those costs with a new, smaller mortgage or a high-maintenance condo fee often results in an annual saving so small that it takes decades to recoup the cost of the move.
Chronology: A Step-by-Step Financial Audit
To determine if your move is a prudent financial decision or a lifestyle purchase, you must treat the transition as a business investment. This requires a four-step audit:
- The One-Time Cost Assessment: List every expense associated with exiting your current home and entering the next. Do not use generic estimates. Get actual quotes for commissions, move-related logistics, and anticipated repairs for the target property. Be pessimistic; if you budget high and come in under, you have a buffer.
- The Annual Carrying Cost Comparison: Create a two-column spreadsheet. Column A is your current home’s annual cost (taxes, insurance, utilities, routine maintenance, and HOA). Column B is the same for the prospective home. Crucially, do not use "rules of thumb" for maintenance. Use your bank statements from the last three years to determine exactly how much you spend on repairs.
- The Break-Even Calculation: Divide your total one-time costs by your annual savings. If the move costs $50,000 and saves you $4,000 a year, your break-even point is 12.5 years. If you are 75 years old, you must ask yourself if you intend to live in the new home past age 88.
- The Non-Financial Ledger: This is the column most people ignore. It is the value of your proximity to long-term doctors, the social support of a neighborhood where you are known, and the "memory equity" built over decades.
Supporting Data: The Reality of Older Adults
The pressure to downsize often ignores the expressed desires of the elderly population. According to the AARP’s 2024 Home and Community Preferences survey, 75% of adults aged 50 and older want to remain in their current homes as long as possible. This is not mere sentimentality; it is a rational desire for stability.
Furthermore, data from Harvard’s Joint Center for Housing Studies highlights the financial reality of this demographic. Because the majority of older homeowners are mortgage-free, they are already enjoying the most cost-effective housing strategy available. When an advisor tells them to "free up equity," they are often suggesting that the client trade a low-cost, paid-off asset for a lower-equity, potentially higher-fee asset.
When looking at the math, consider the "mortgage trap." If you are moving from a paid-off home into a smaller one that requires a new mortgage at current interest rates, you may be trading a 0% interest debt for a 6% or 7% interest debt. This can lead to a monthly cash-flow situation that is actually worse than the one you left behind.
Official Responses and Regulatory Shifts
The real estate landscape changed significantly in August 2024 due to the National Association of Realtors (NAR) settlement. The practice of automatically displaying offers of buyer-agent compensation has ended. For the downsizer, this means that the "cost of selling" is now more negotiable—and more transparent—than ever.
Sellers are no longer inherently responsible for the buyer-agent’s commission in the same way they were historically. However, sellers may still choose to offer these incentives to attract buyers. This change means that homeowners must be more sophisticated in their negotiations. When interviewing agents, ask specifically how the new settlement terms will impact your net proceeds. Do not assume the "standard" commission rate; in a high-stakes transaction, a few percentage points of commission can be the difference between a successful move and an expensive mistake.
Implications: When the Move Makes Sense
If the math is unfavorable, does that mean you should never move? Absolutely not. It simply means you should stop calling the move a "financial decision."
There are valid, non-financial reasons to relocate:
- The "Care Gap": If your home layout poses a legitimate risk to your health—such as inaccessible stairs or a layout that prohibits wheelchair use—the move is a health necessity, not a fiscal one.
- Proximity to Caregivers: If you are isolated, moving closer to family to ensure your long-term well-being is an invaluable investment.
- The "Life Audit": If you feel that your home is trapping you in a version of your life that no longer exists, moving can be a powerful psychological reset.
However, the implication is clear: be honest about the cost. If you are moving for convenience or proximity, acknowledge that you are paying a premium for a lifestyle upgrade. Do not look for a financial return on a move that is, by its nature, an expense.
Final Guidance for the Prospective Seller
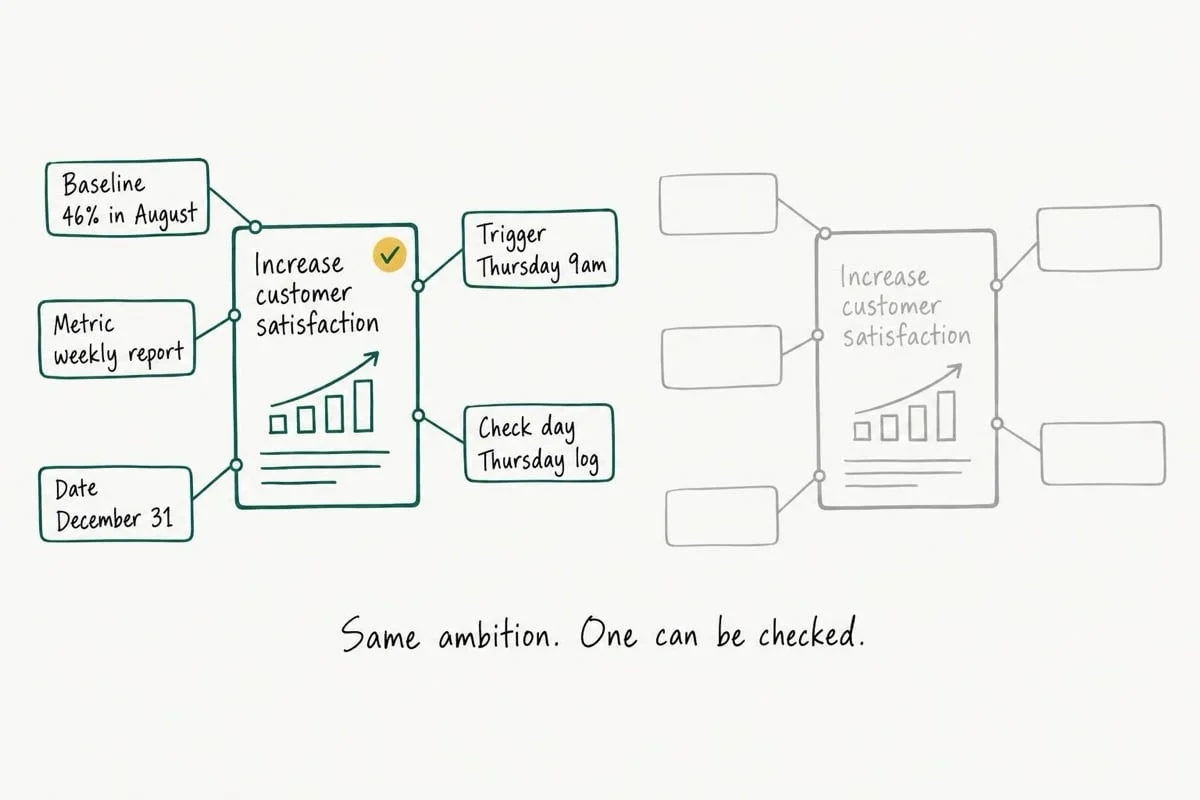
Before calling an agent, perform the "One-Page Audit." If your break-even period exceeds your intended residency, you are buying a lifestyle change, not an investment. If you find that the house is simply "too much," explore the middle ground first: hire a landscaping crew, install a stairlift, or pay for a bi-weekly cleaning service. Compare the cost of these services against the cost of the move.
Often, the most "financially smart" decision is to stay in the home you have already paid for, treating the house not as a stock portfolio to be liquidated, but as the foundation for the next decade of your life. By stripping away the pressure to downsize, you regain the autonomy to choose the home that best fits your actual needs—not the one that fits a general rule of thumb.