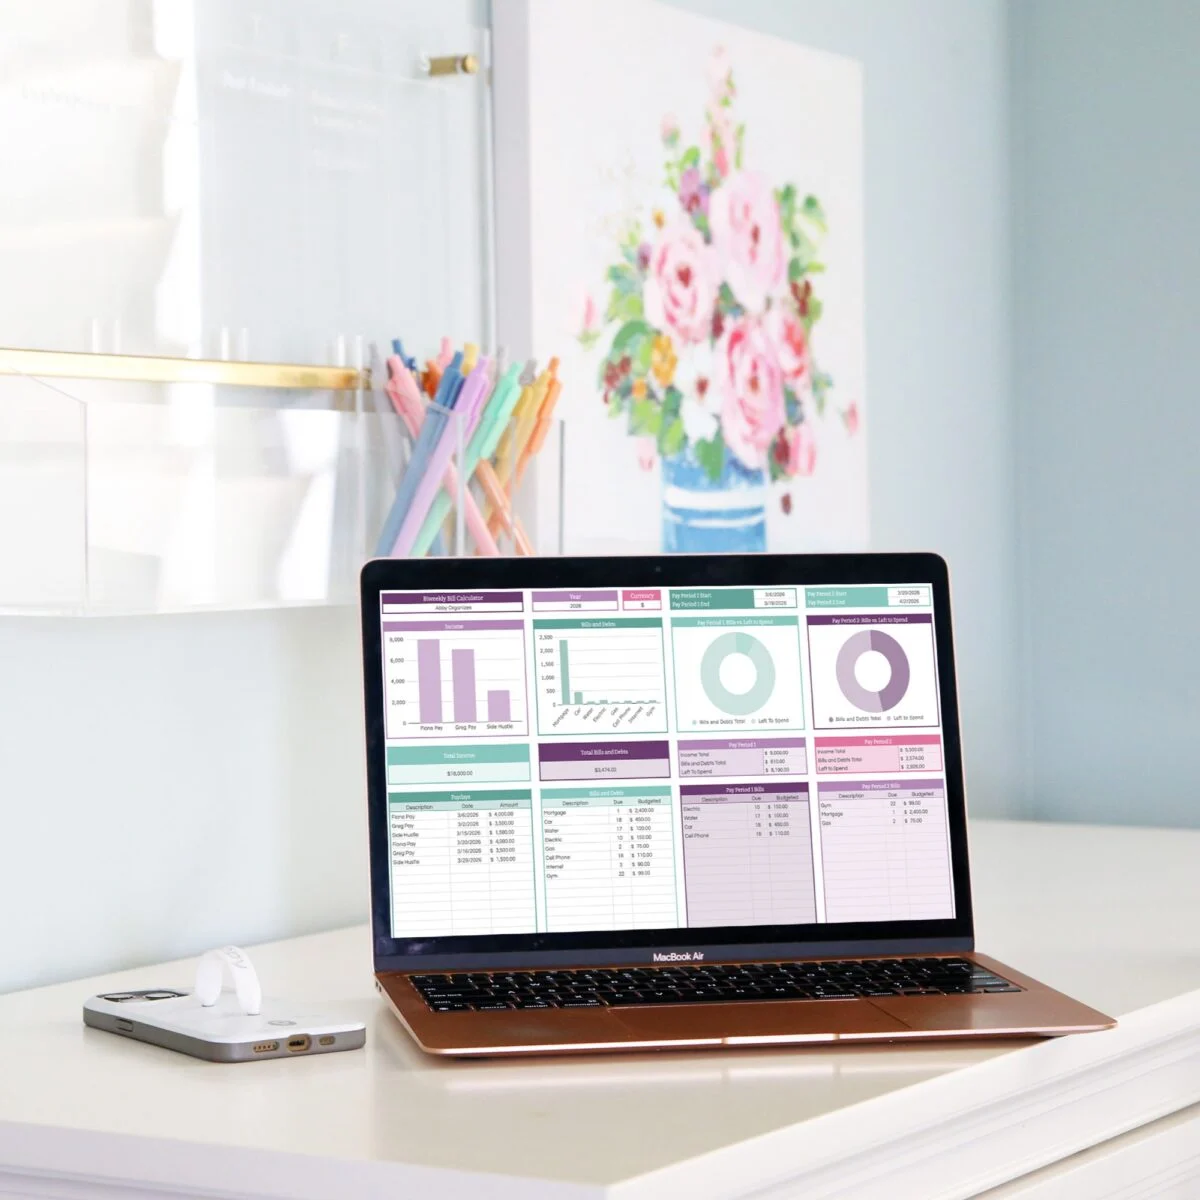
Main Facts: Conquering the Biweekly Budgeting Challenge
For millions of working professionals, the biweekly pay schedule—yielding 26 paychecks annually—is a standard reality of modern employment. Yet, despite its prevalence, aligning a monthly financial life around a paycheck schedule that arrives every 14 days remains one of the most stubborn roadblocks in personal finance. Because pay periods frequently span across two distinct calendar months, standard budgeting advice often falls short, leaving households feeling overwhelmed, disorganized, and vulnerable to overspending.
At its core, a biweekly budget requires translating an income rhythm that desynchronizes with the standard 30-day calendar. While semi-monthly paychecks arrive precisely twice a month (totaling 24 paychecks a year, usually on fixed dates like the 1st and 15th), biweekly paychecks shift across the calendar, meaning two months out of every year will naturally yield a coveted third paycheck. Recognizing this distinction is the first step toward transforming what many perceive as a confusing financial puzzle into a powerful tool for wealth accumulation.
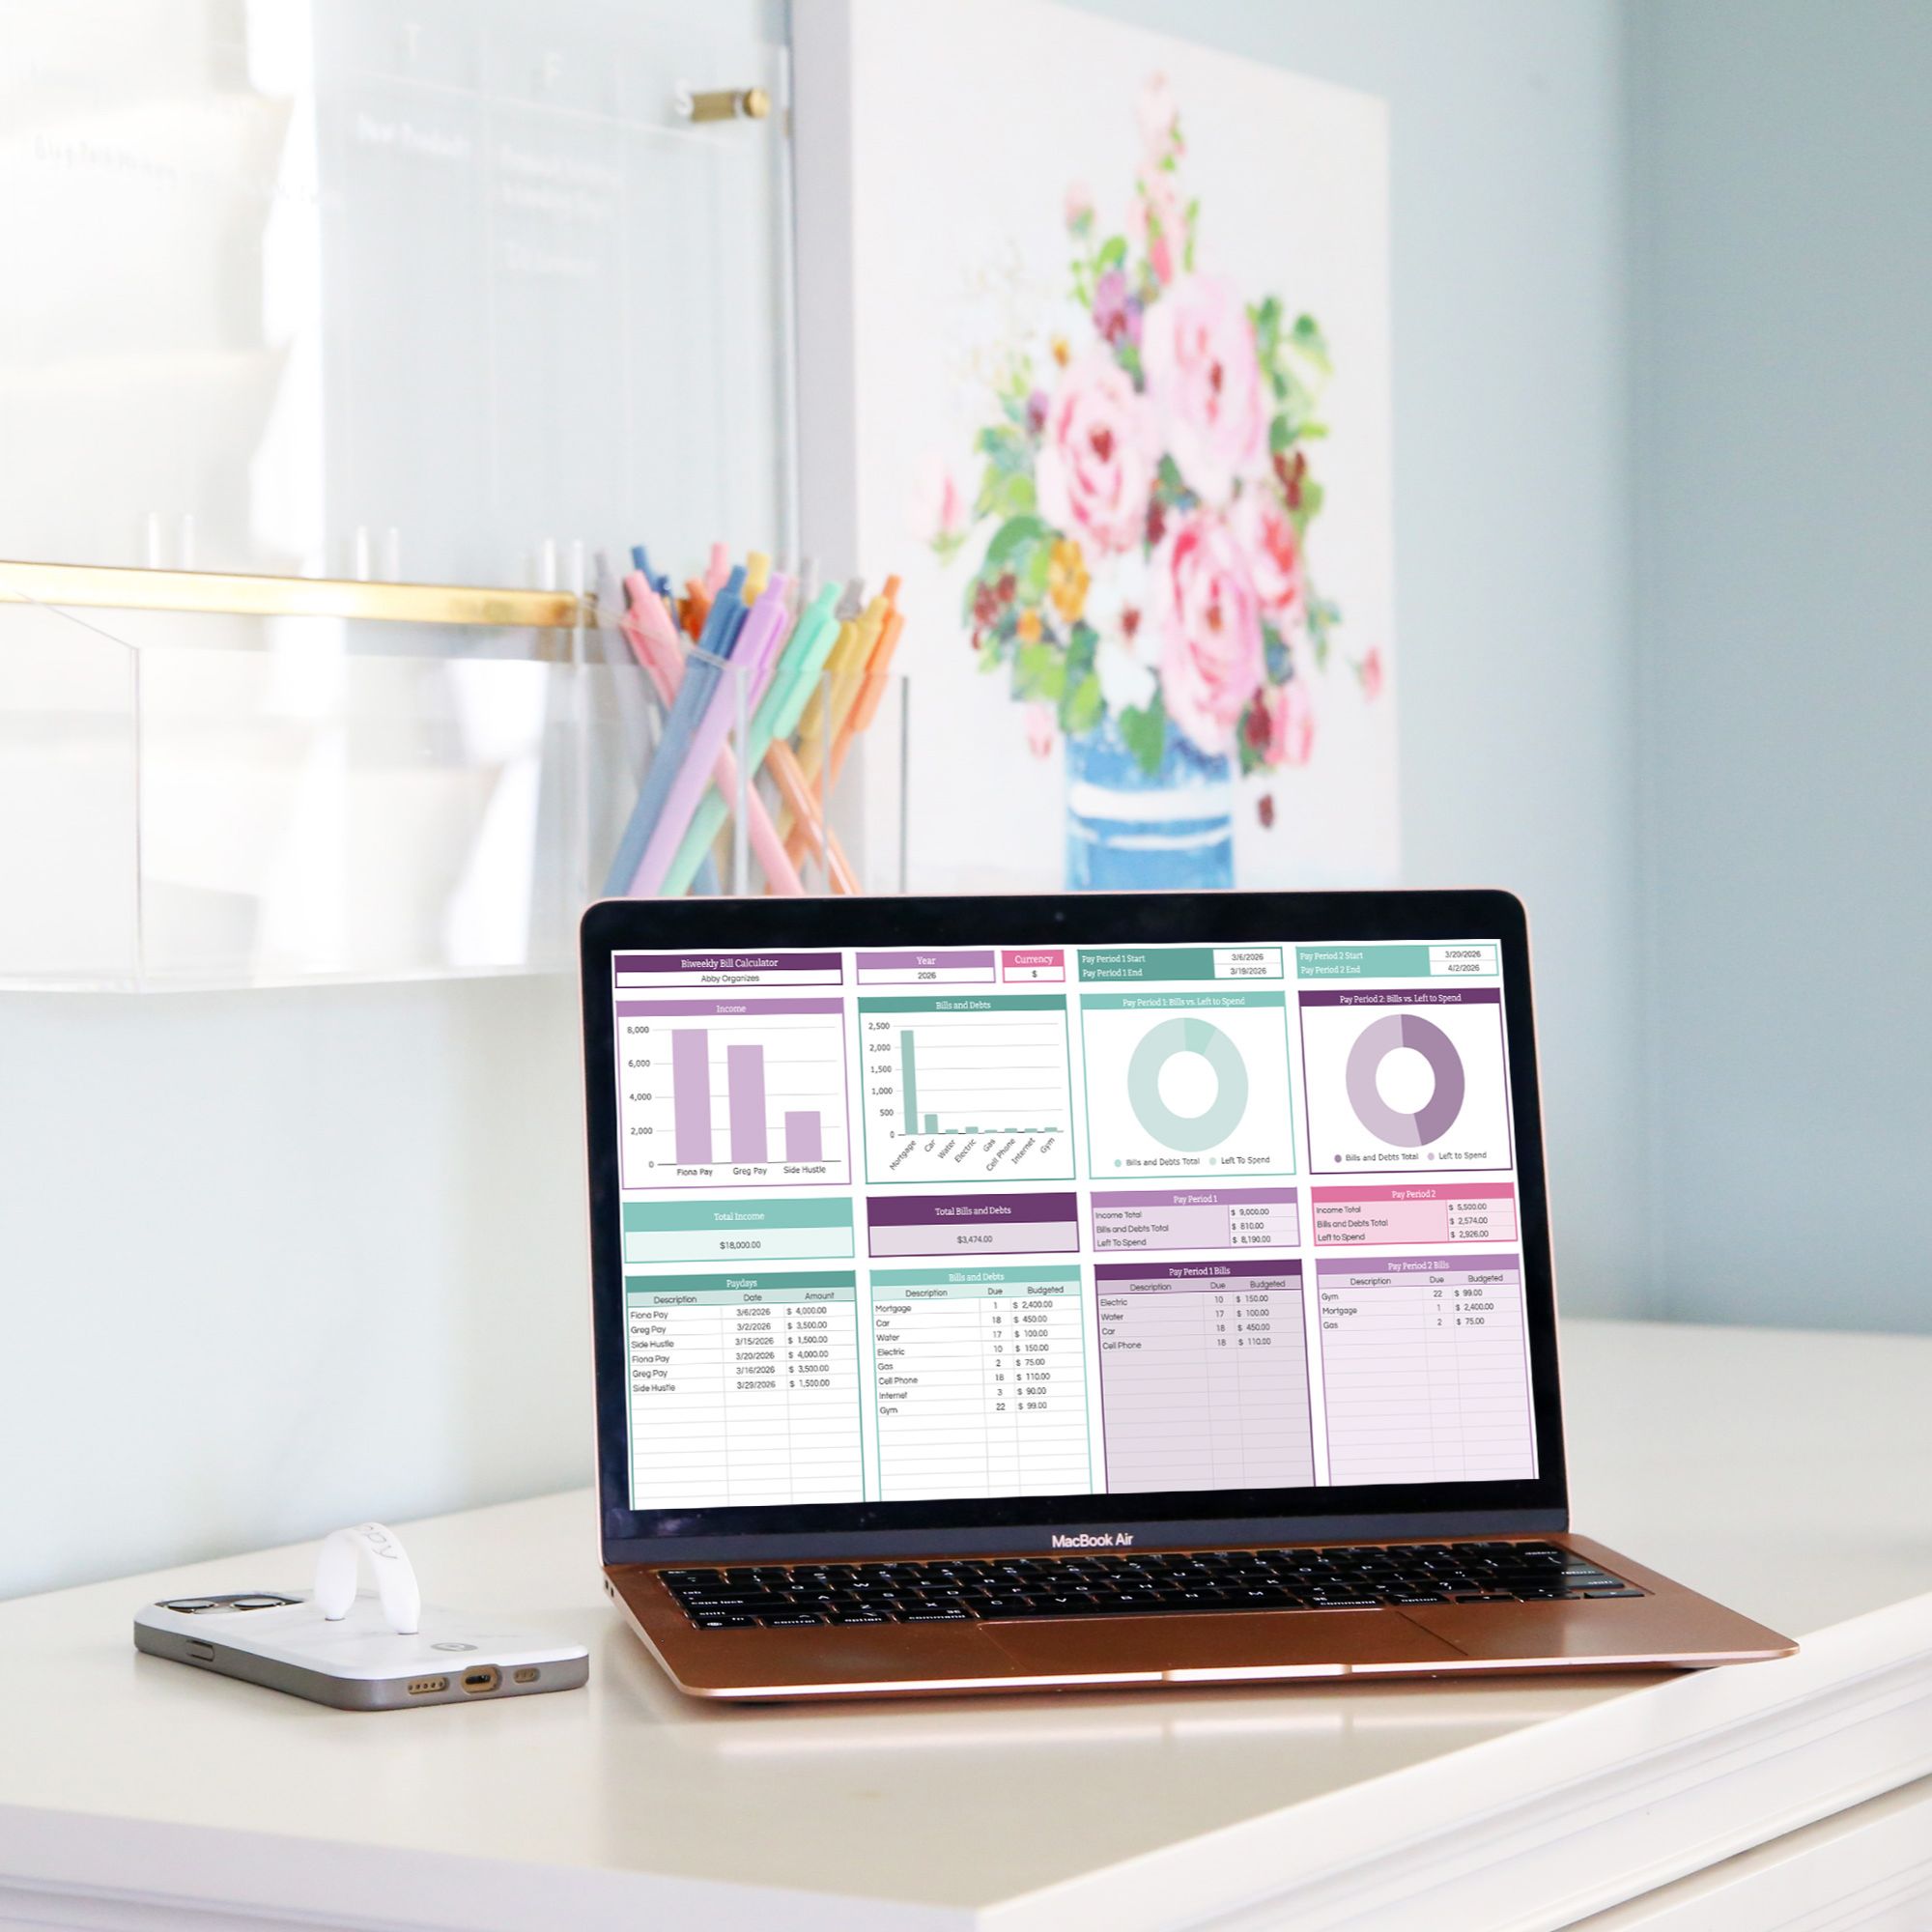
To simplify this process, financial organizers and digital template creators have developed streamlined workflows and automated calculation tools. By auditing net income, systematically inventorying recurring obligations, smoothing out variable spending, and establishing dedicated buffer funds, households can eliminate the anxiety traditionally associated with irregular pay dates and put themselves on a firm trajectory toward fiscal stability.
Chronology: The Step-by-Step Implementation Framework
Transitioning from financial uncertainty to a reliable, structured routine requires a deliberate, chronological sequence of actions. Implementing a biweekly budget successfully involves five foundational phases designed to map out, execute, and monitor household cash flow.
Step 1: Calculate Your True Net Income Base
The foundation of any working budget is a precise understanding of available capital. Households must pin down the exact net income—the "take-home" pay—generated by each biweekly paycheck.
- Consolidate Sources: If expenses are shared with a spouse or domestic partner, or if individuals maintain secondary revenue streams through side hustles, these funds must be incorporated into the master calculation.
- Avoid Projections: Relying on gross income or estimated figures invites budget deficits. Only verified net figures should serve as the baseline for household spending limits.
Step 2: Audit and Distribute Your Bills and Debts
Once income is established, the next phase requires a thorough historical review of the previous month’s bank and credit card statements.
- Inventory Obligations: Compile a comprehensive list of all recurring financial commitments, including housing costs, utility bills, insurance premiums, loan installments, and subscription services. Note the exact bill name, due date, and typical amount.
- Account for Fluctuations: For variable utilities like water or electricity, record a conservative estimate slightly higher than historical averages. A surplus at month’s end is manageable; a cash shortfall creates unnecessary debt.
- Balance the Halves: Evaluate how expenses are distributed across the month. Ideally, the financial obligations falling due in the first half of the month should roughly equal those in the second half. If a major disparity exists, contact service providers to request a due-date adjustment—a common administrative request that most companies accommodate.
Step 3: Outline and Estimate Variable Expenses
With fixed bills evenly distributed, attention turns to discretionary and variable living costs. These categories include groceries, automotive fuel, clothing, dining out, and household supplies.
- Establish Baselines: For households new to budgeting, spending should be tracked for an initial 30-day observation period without strict limits. This baseline data reveals true spending habits.
- Set Realistic Caps: Following the observation phase, assign fixed maximum allocations to each variable category to prevent lifestyle creep and impulsive purchasing.
Step 4: Account for Savings Contributions and Buffer Funds
A robust budget does not merely account for survival; it builds future security. Savings allocations—ranging from emergency reserves and retirement contributions to specific sinking funds for travel or vehicle maintenance—must be written directly into the monthly plan.
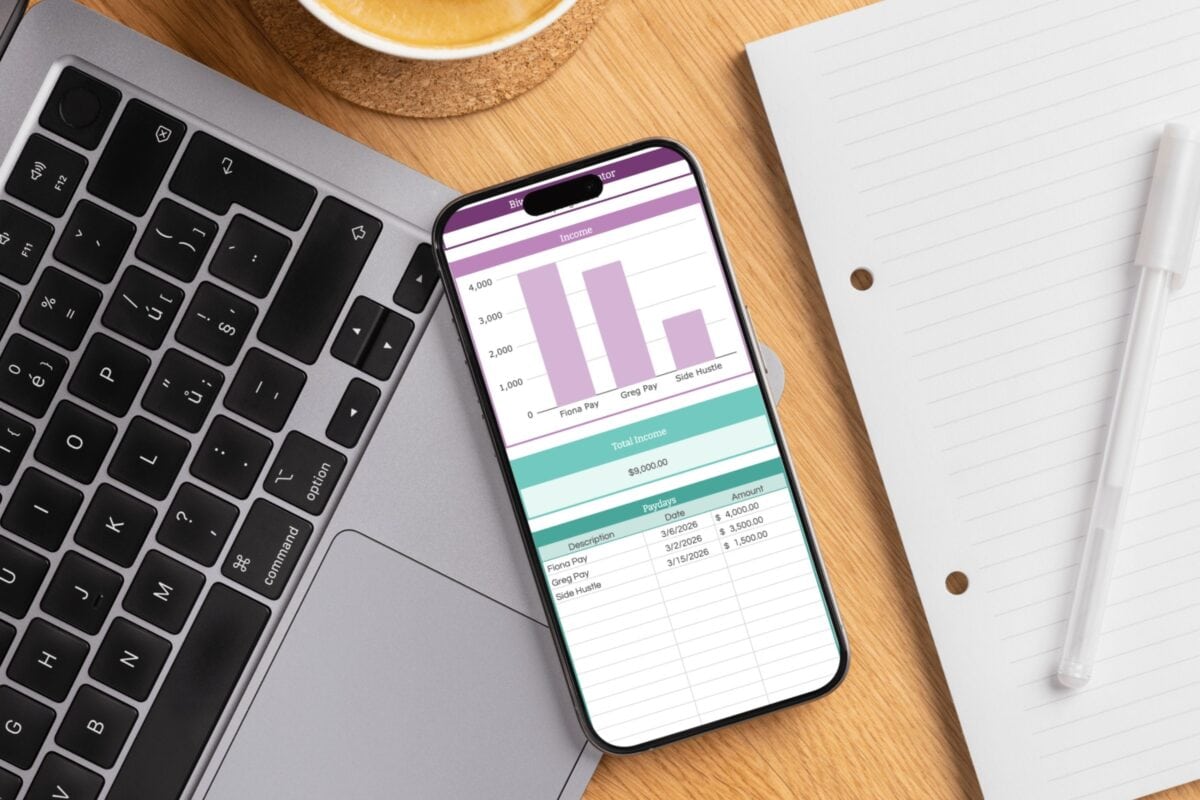
- Build a Buffer Fund: Biweekly earners frequently encounter awkward calendar alignments where a bill falls just days before a paycheck arrives. Establishing a dedicated buffer fund provides a minor liquidity cushion to bridge these gaps, with the strict rule that borrowed funds are replenished immediately upon the arrival of the next direct deposit.
Step 5: Execute Weekly Tracking and Maintenance
A budget is a living document that requires ongoing oversight. Rather than reviewing numbers monthly—when it is too late to correct overspending—effective managers dedicate a brief window, such as 20 minutes on Friday mornings, to log transactions into a digital spreadsheet or tracking application. This consistent touchpoint allows for micro-adjustments in real time.
Supporting Data: The Power of the "Third Paycheck" Phenomenon
One of the most compelling advantages of a biweekly pay schedule is the mathematical reality of the calendar: 52 weeks divided by two equals 26 pay periods, while the standard calendar year contains 12 months. This structural mismatch generates a mathematical bonus.
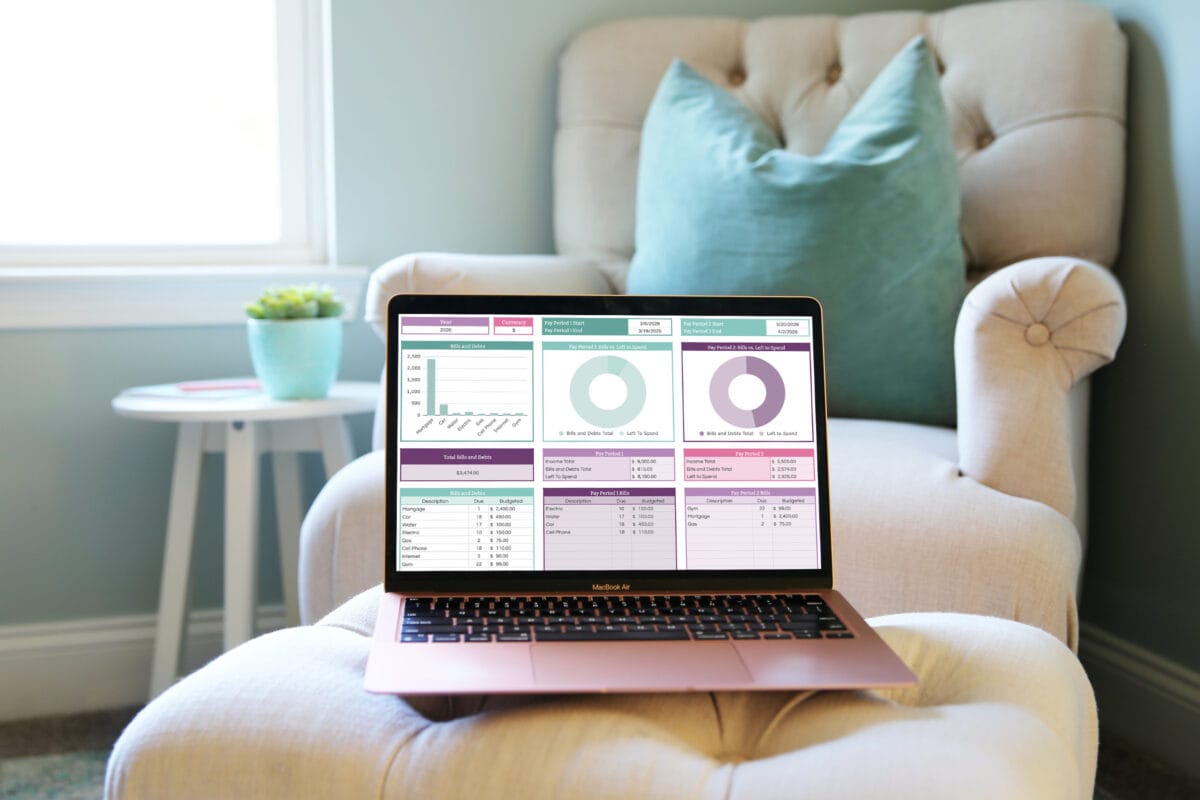
When households design their primary operating budget around the income of just two paychecks per month, all standard living expenses, debt payments, and baseline savings goals are completely covered within those 24 pay cycles. Consequently, the two months out of the year that feature a third paycheck represent a pure financial surplus.
- Accelerated Debt Liquidation: Directing a surprise third paycheck toward high-interest credit card debt or principal mortgage reduction can shave years off repayment timelines and save thousands of dollars in cumulative interest.
- Immediate Wealth Building: Depositing these surplus funds directly into emergency reserves or long-term investment portfolios rapidly accelerates net worth growth without requiring daily deprivation.
- Pre-Planned Allocations: Financial planners emphasize the importance of ranking personal financial goals in advance. When the third paycheck lands, having a pre-determined priority list eliminates emotional decision-making, ensuring the windfall is maximized rather than absorbed by lifestyle inflation.
Official Responses and Expert Insights
Personal finance educators and consumer advocates consistently highlight the psychological barriers that derail traditional budgeting efforts. According to behavioral researchers in household economics, complexity is the primary driver of budget abandonment. When a system requires advanced mathematical forecasting to align biweekly deposits with monthly billing cycles, cognitive fatigue sets in.
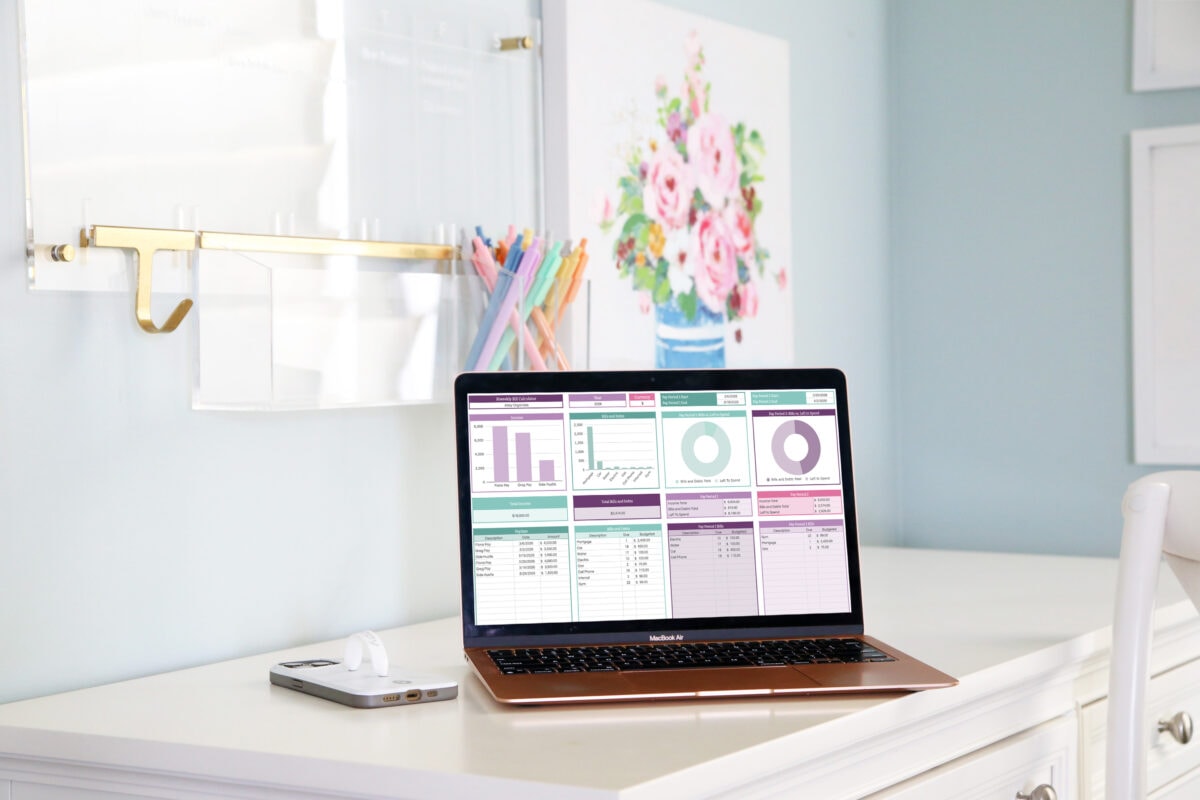
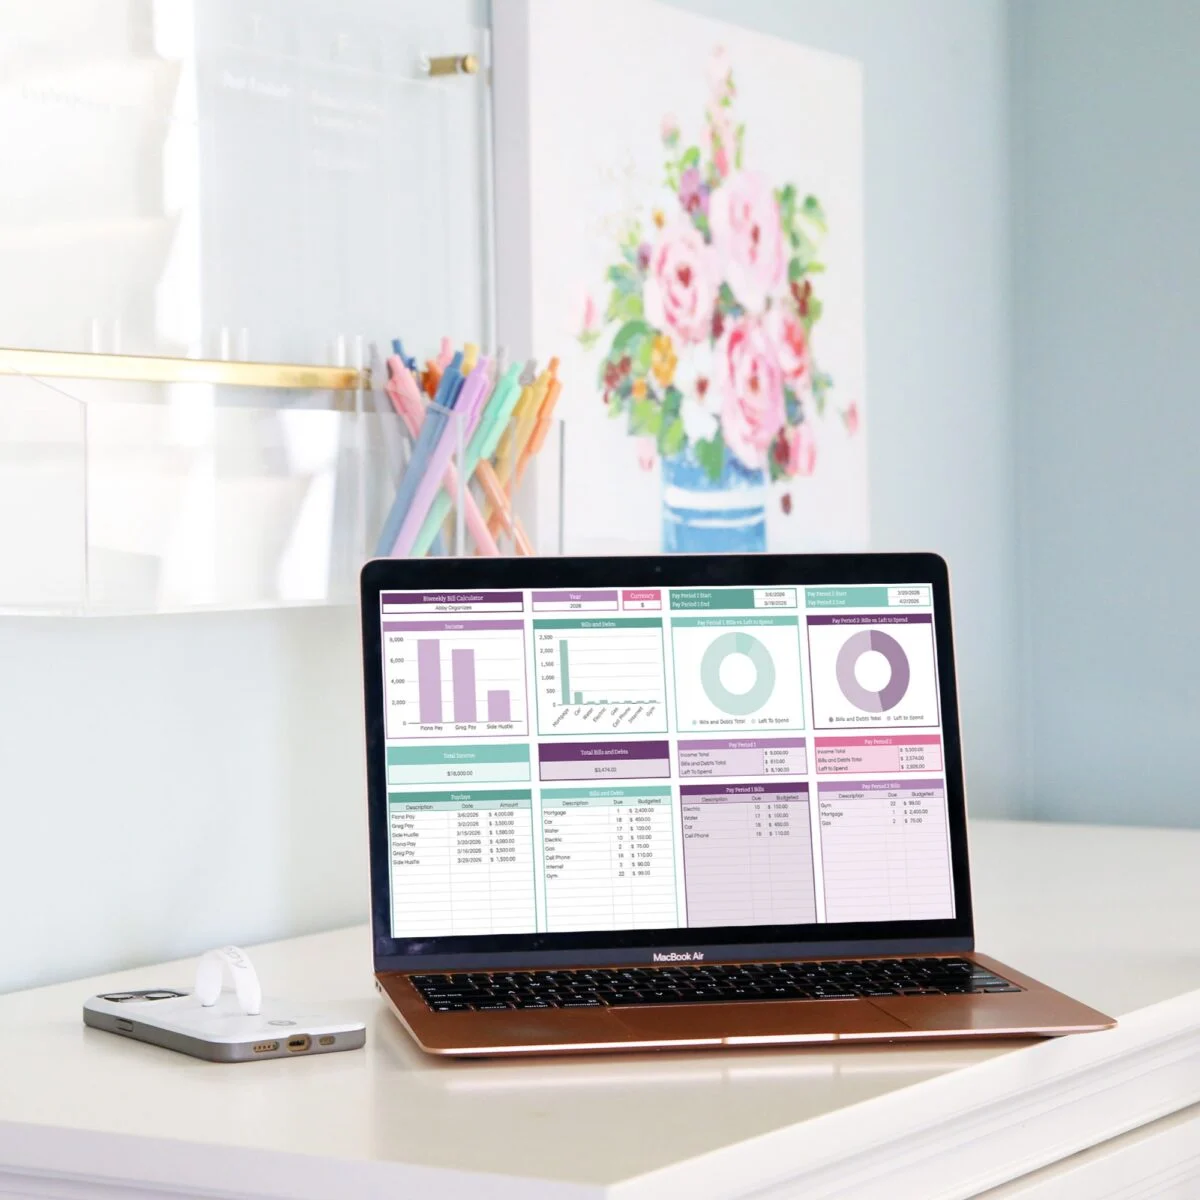
"The moment a financial plan feels overly cumbersome, people throw in the towel," notes leading household organization and budgeting strategist Abby Lawson. "The secret to sustainable personal finance isn’t strict deprivation; it is building a repeatable, friction-free system that removes guesswork. When you utilize digital calculators and automated tracking templates to map out your pay periods, you eliminate the mental friction that causes people to give up."
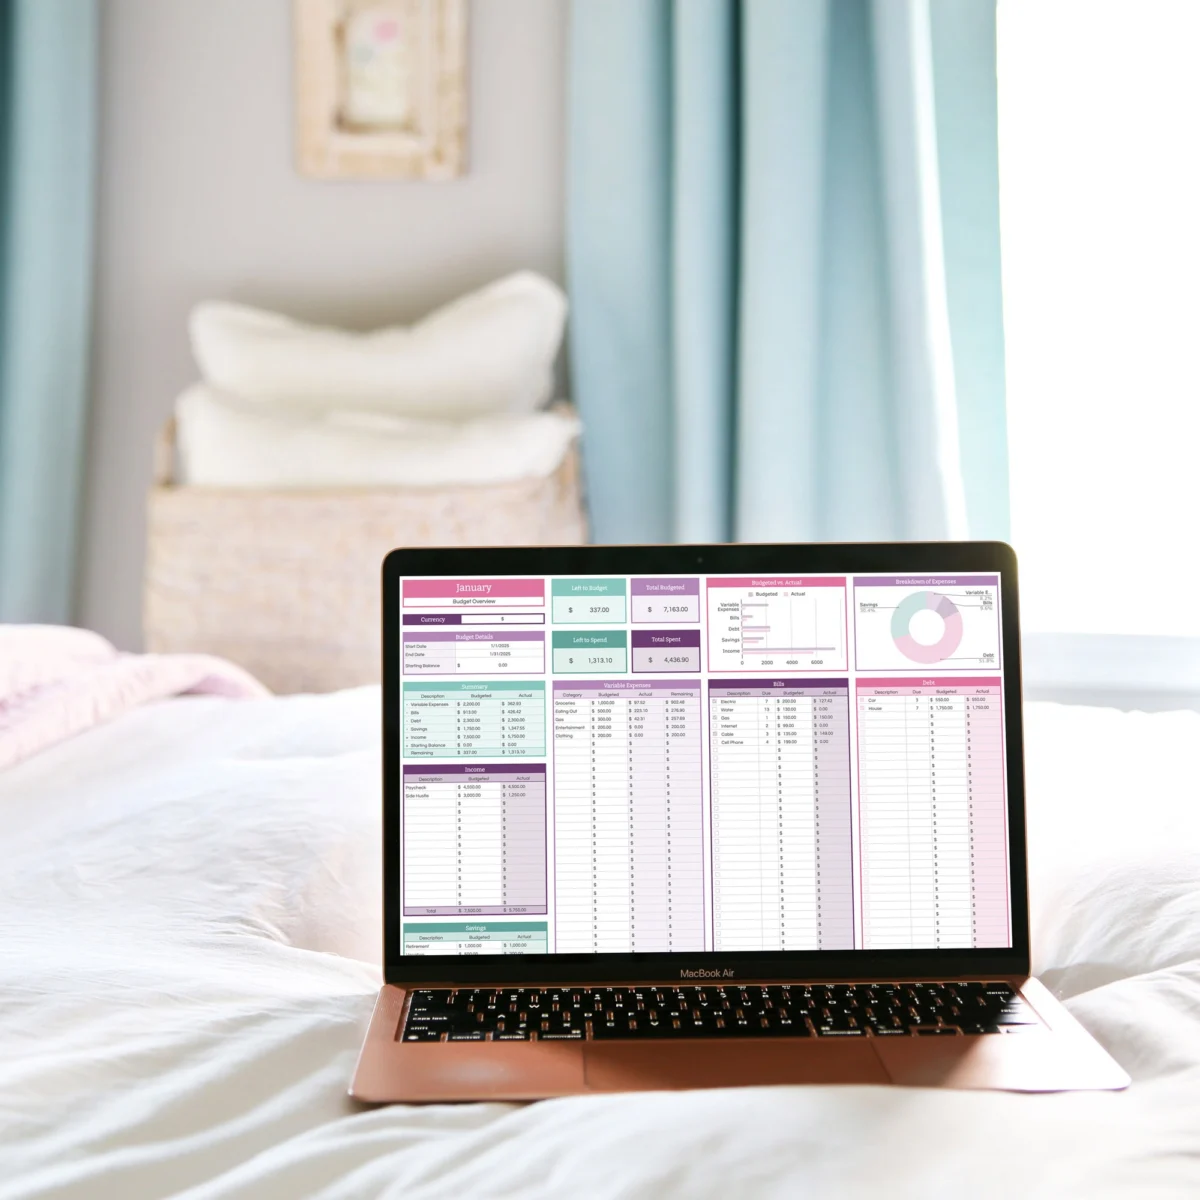
Furthermore, banking industry analysts point out that automated bill payment systems, when synchronized with biweekly pay calendars, drastically reduce instances of accidental overdrafts and missed payment penalties. Financial institutions increasingly advocate for digital spreadsheet tools and customized bill calculators that visually map out exactly which paycheck covers specific liabilities, turning abstract monetary concepts into clear, visual workflows.

Implications: Long-Term Financial Health and Behavioral Change
The transition to a structured biweekly budgeting framework carries profound implications for long-term household economic resilience.
- Reduction of Financial Stress: Money-related anxiety is a leading contributor to chronic stress and workplace distraction. By establishing visibility over future cash flow and maintaining a dedicated buffer fund, households insulate themselves against unexpected calendar anomalies.
- Shift from Reactive to Proactive Management: Without a system, biweekly earners often fall into a paycheck-to-paycheck mentality simply because paydays do not align neatly with rent, mortgage, and utility due dates. Implementing a deliberate distribution strategy shifts the household from a reactive stance—scrambling to cover bills as they arrive—to a proactive posture where every dollar is assigned a purpose before it hits the bank account.
- Sustainable Wealth Accumulation: Perhaps the most significant implication is the behavioral shift observed in individuals who track their spending weekly. Regular engagement with financial data fosters heightened financial literacy and mindfulness. Households naturally begin making smarter spending decisions and accelerating savings contributions, proving that financial health is achieved not through restriction, but through intentional organization, clear systems, and consistency.