In the landscape of modern American adulthood, the milestones of financial stability—homeownership, robust retirement savings, and debt-free living—often feel like moving targets. For Brian and Michael, a 34-year-old couple living in central Connecticut, these goals are not merely abstract desires but immediate, pressing priorities. Despite holding steady jobs in the public and non-profit sectors, the couple finds themselves at a crossroads, grappling with the lingering weight of consumer debt and the desire to build a permanent, secure foundation for their future.
This analysis explores their current financial trajectory, the hurdles they face, and the strategic roadmap proposed to help them achieve the "next level of adulting."

The Human Element: Profiles in Stability and Struggle
Brian and Michael, who have been together since 2013, represent a demographic often caught in the "middle-class squeeze." Brian serves as a quality assurance manager for a state-run hospital, while Michael works as a project coordinator for a behavioral health agency, supplemented by his work as an advocate and disability leadership coordinator.
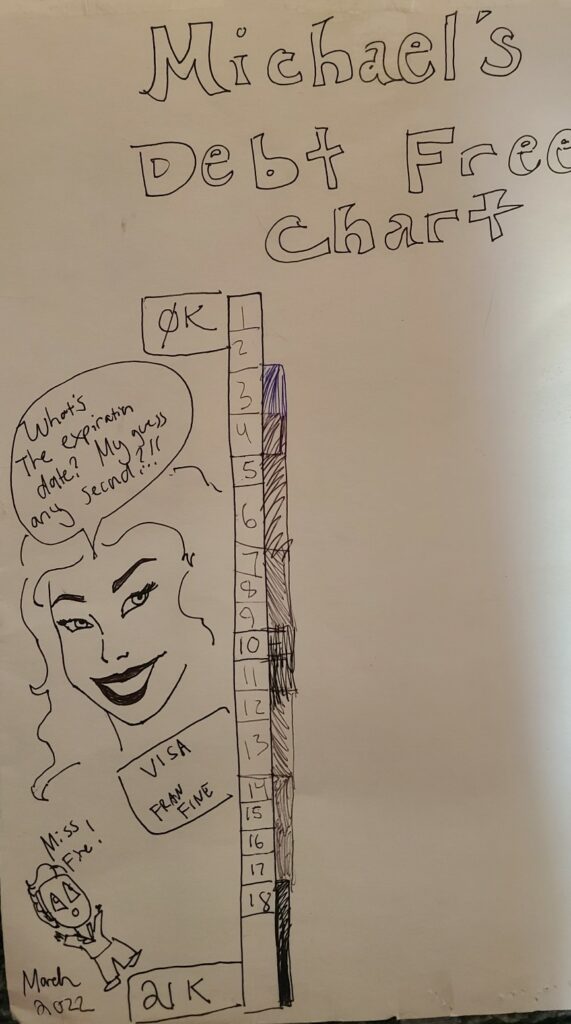
Both individuals are highly educated and deeply committed to their professional roles, yet they report a sense of profound "financial shame." This sentiment is not born of a lack of effort, but rather a perceived misalignment between their current reality—which includes a $28,259 consumer debt load—and their long-term vision of homeownership, marriage, and a legacy-building business.
Chronology of Challenges: The Road to 2023
The couple’s current financial anxiety is largely rooted in the volatility of the 2022–2023 period. Previously, the pair resided in a modest 600-square-foot studio apartment, maintaining a low cost of living that allowed them to forecast a return to the housing market. However, a forced relocation due to the competitive and expensive rental market, compounded by unexpected veterinary expenses for their two kittens, derailed their original timeline.
Key Turning Points:
- August 2022: The couple’s original plan to re-enter the housing market in late 2023 is set in motion.
- Late 2022/Early 2023: Unplanned moving costs and significant veterinary bills begin to erode their liquid savings.
- Mid-2023: Brian and Michael realize their consumer debt has reached a level that necessitates an external, objective review of their financial habits.
Supporting Data: The Financial Snapshot
To understand their situation, one must look at the hard numbers. The couple brings in a combined annual gross income of $167,544, with a net annual income of $109,455. Their monthly expenses currently sit at $8,035.
Debt Overview
| Creditor | Balance | Interest Rate |
|---|---|---|
| Brian’s Visa (SCU) | $16,057 | 0% (until Nov 2023, then 17.99%) |
| Michael’s Visa | $9,700 | 10.99% |
| Brian’s Visa (Navy Fed) | $2,503 | 0.99% (until Nov 2023, then 17.74%) |
| Total | $28,259 | — |
Despite the debt, the couple possesses a notable array of assets, including a combined retirement portfolio of over $91,000. Brian’s access to a state pension, 403b, and 457 plan represents a "triple crown" of retirement security, provided he stays on his current career path.
Expert Analysis: The "Frugalwoods" Perspective
In response to the couple’s request for guidance, financial experts emphasize that the situation is far from dire. The primary issue is not a lack of income, but a lack of structural discipline.
The Case for Expense Tracking
The most immediate recommendation is the implementation of a rigorous expense-tracking system. With a net annual income of $109,455 and spending of $96,414, there is a theoretical annual surplus of $13,041. If tracked correctly, this surplus could be entirely redirected toward debt principal. The expert consensus is that "money is a spreadsheet problem," meaning it can be solved with granular data and consistent behavior.
Strategic Debt Reduction
The experts advise a "no-spend" approach to non-essential categories. By cutting discretionary spending—such as gifts, home goods, and non-essential personal care—the couple could theoretically free up nearly $4,500 per month. At this rate, the entirety of their $28,259 debt could be retired in roughly six to seven months.
Implications for the Future
The couple’s desire for homeownership is valid, but the experts warn against rushing into the market. Before purchasing a home, the following hierarchy of needs must be satisfied:
- Debt Elimination: High-interest debt acts as a negative investment. It must be neutralized before capital is diverted to a down payment.
- Emergency Fund Stabilization: Currently, the couple’s cash reserves cover only about one month of expenses. A robust emergency fund should cover three to six months of essential living costs to prevent future "debt-payoff-debt" cycles.
- Retirement Optimization: With over $80,000 in potential annual tax-advantaged contribution space, the couple is encouraged to maximize their workplace accounts before focusing on real estate.
The Graduate School Dilemma
Regarding Brian’s interest in a master’s degree, the advice is stark: unless there is a guaranteed, documented, and significant salary increase associated with the credential, it is viewed as an "unhelpful detour." In the current economic climate, the opportunity cost of lost income and tuition fees outweighs the potential for professional prestige unless the degree translates into immediate, tangible ROI.
Conclusion: A Path Toward Stability
Brian and Michael are not failing; they are merely experiencing the friction common to many professionals in their thirties. Their assets—including a pension, a high savings rate potential, and stable, high-value employment—provide a strong base.
The transition from "financial shame" to "financial confidence" requires a shift in mindset. By prioritizing debt elimination over lifestyle inflation and treating their retirement contributions as a fixed, non-negotiable expense, the couple can move away from the cycle of debt and toward their goal of long-term security. The next ten years will be defined by whether they choose to treat their income as a tool for wealth creation or as a mechanism for consumption. With a structured plan, the former is well within their reach.