By Financial News Desk
For millions of freelancers, gig economy workers, commission-based sales professionals, and small business owners, the monthly financial cycle is a high-stakes guessing game. While a traditional nine-to-five position offers the psychological comfort of a predictable paycheck hitting the bank account on the exact same days every month, an irregular income introduces a distinct set of financial complexities.
Yet, financial planners and seasoned self-employed professionals increasingly emphasize that managing variable revenue streams is not an impossible puzzle. In fact, developing a budget when your earnings fluctuate from month to month can ultimately cultivate a more resilient financial foundation than a fixed salary ever could.
Main Facts: The Reality of Variable Earnings
The modern workforce has undergone a seismic shift. According to recent labor and economic data, a significant percentage of the workforce now relies entirely or partially on non-traditional income sources. From seasonal contractors and real estate agents to independent creators and entrepreneurs, households surviving on fluctuating paychecks face unique budgeting hurdles.
The primary challenge lies in the psychological friction associated with uncertainty. When income varies widely, traditional budgeting models—which typically rely on allocating exact, predetermined dollar amounts to fixed and discretionary categories—often collapse. If a household budgets based on an optimistic or average earning month, a subsequent slow month can instantly trigger a cash-flow crisis, forcing families to lean heavily on credit cards or deplete their savings.
However, financial experts note that shifting the paradigm changes everything. Rather than viewing an irregular income as an impediment to financial stability, households can adopt targeted strategies that transform variable cash flow into a manageable, predictable system.

Chronology: Overcoming the Fear of the Unknown
For many individuals, the journey to mastering an irregular income begins with avoidance. Historically, many households put off budgeting for years simply because they believed their financial volatility made the exercise futile.
Phase 1: Recognition and Mindset Shift
The first turning point usually occurs when individuals realize that not knowing where their money is going is far more stressful than facing the numbers. Once people sit down to analyze their historical spending data, a profound realization typically sets in: budgeting with a variable income is not only possible, but it is actually more crucial than budgeting with a fixed salary. Because you cannot count on a uniform influx of cash, understanding exact expenditures becomes the ultimate safeguard.
Phase 2: Establishing the Baseline
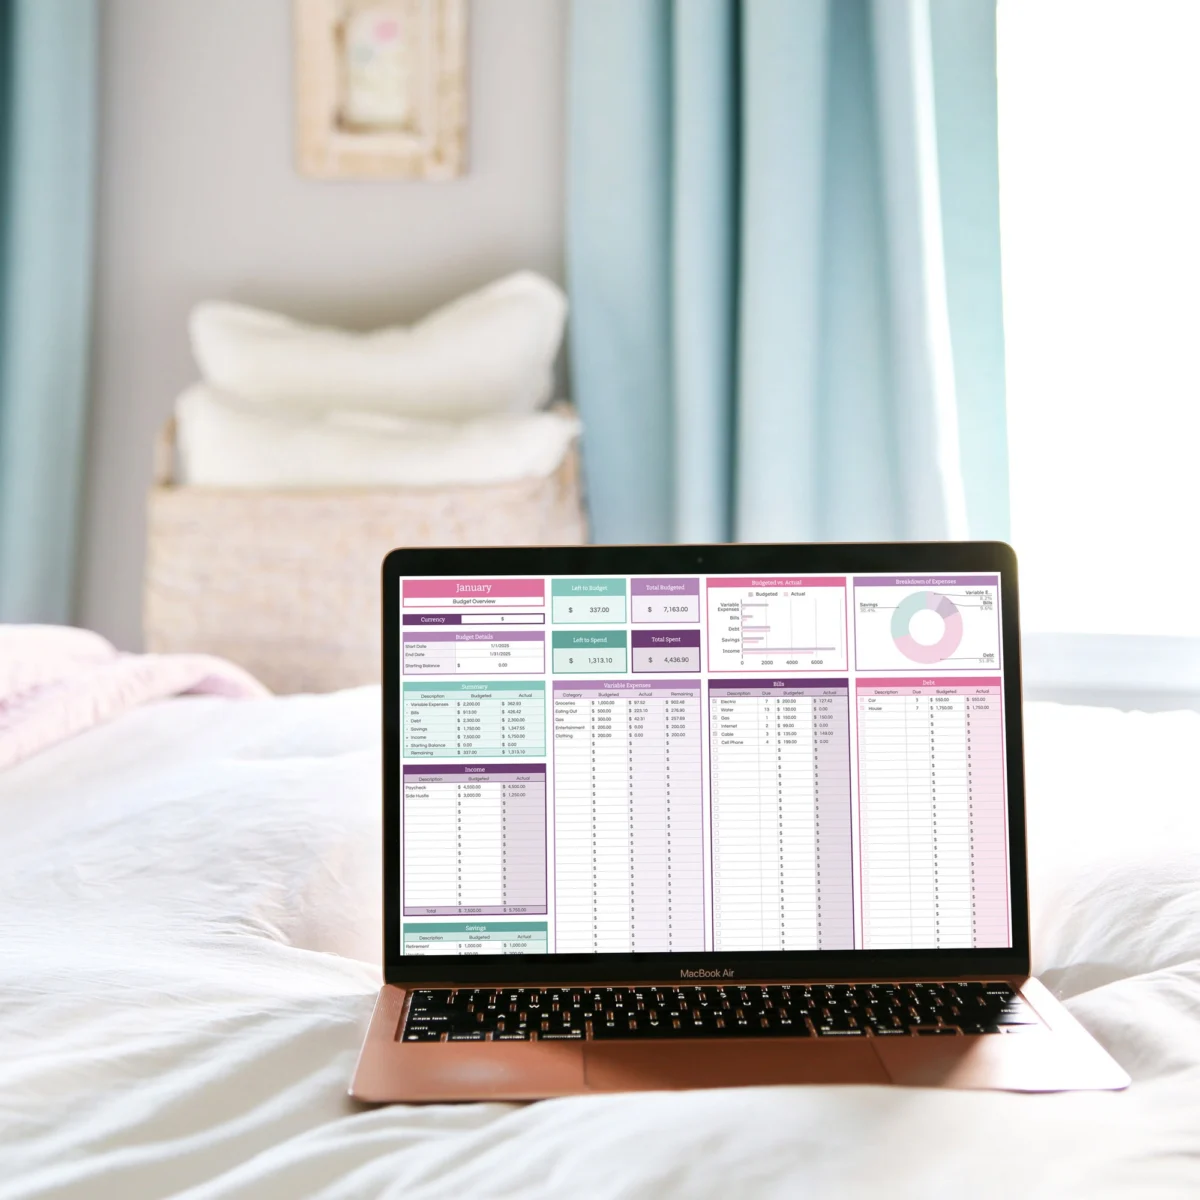
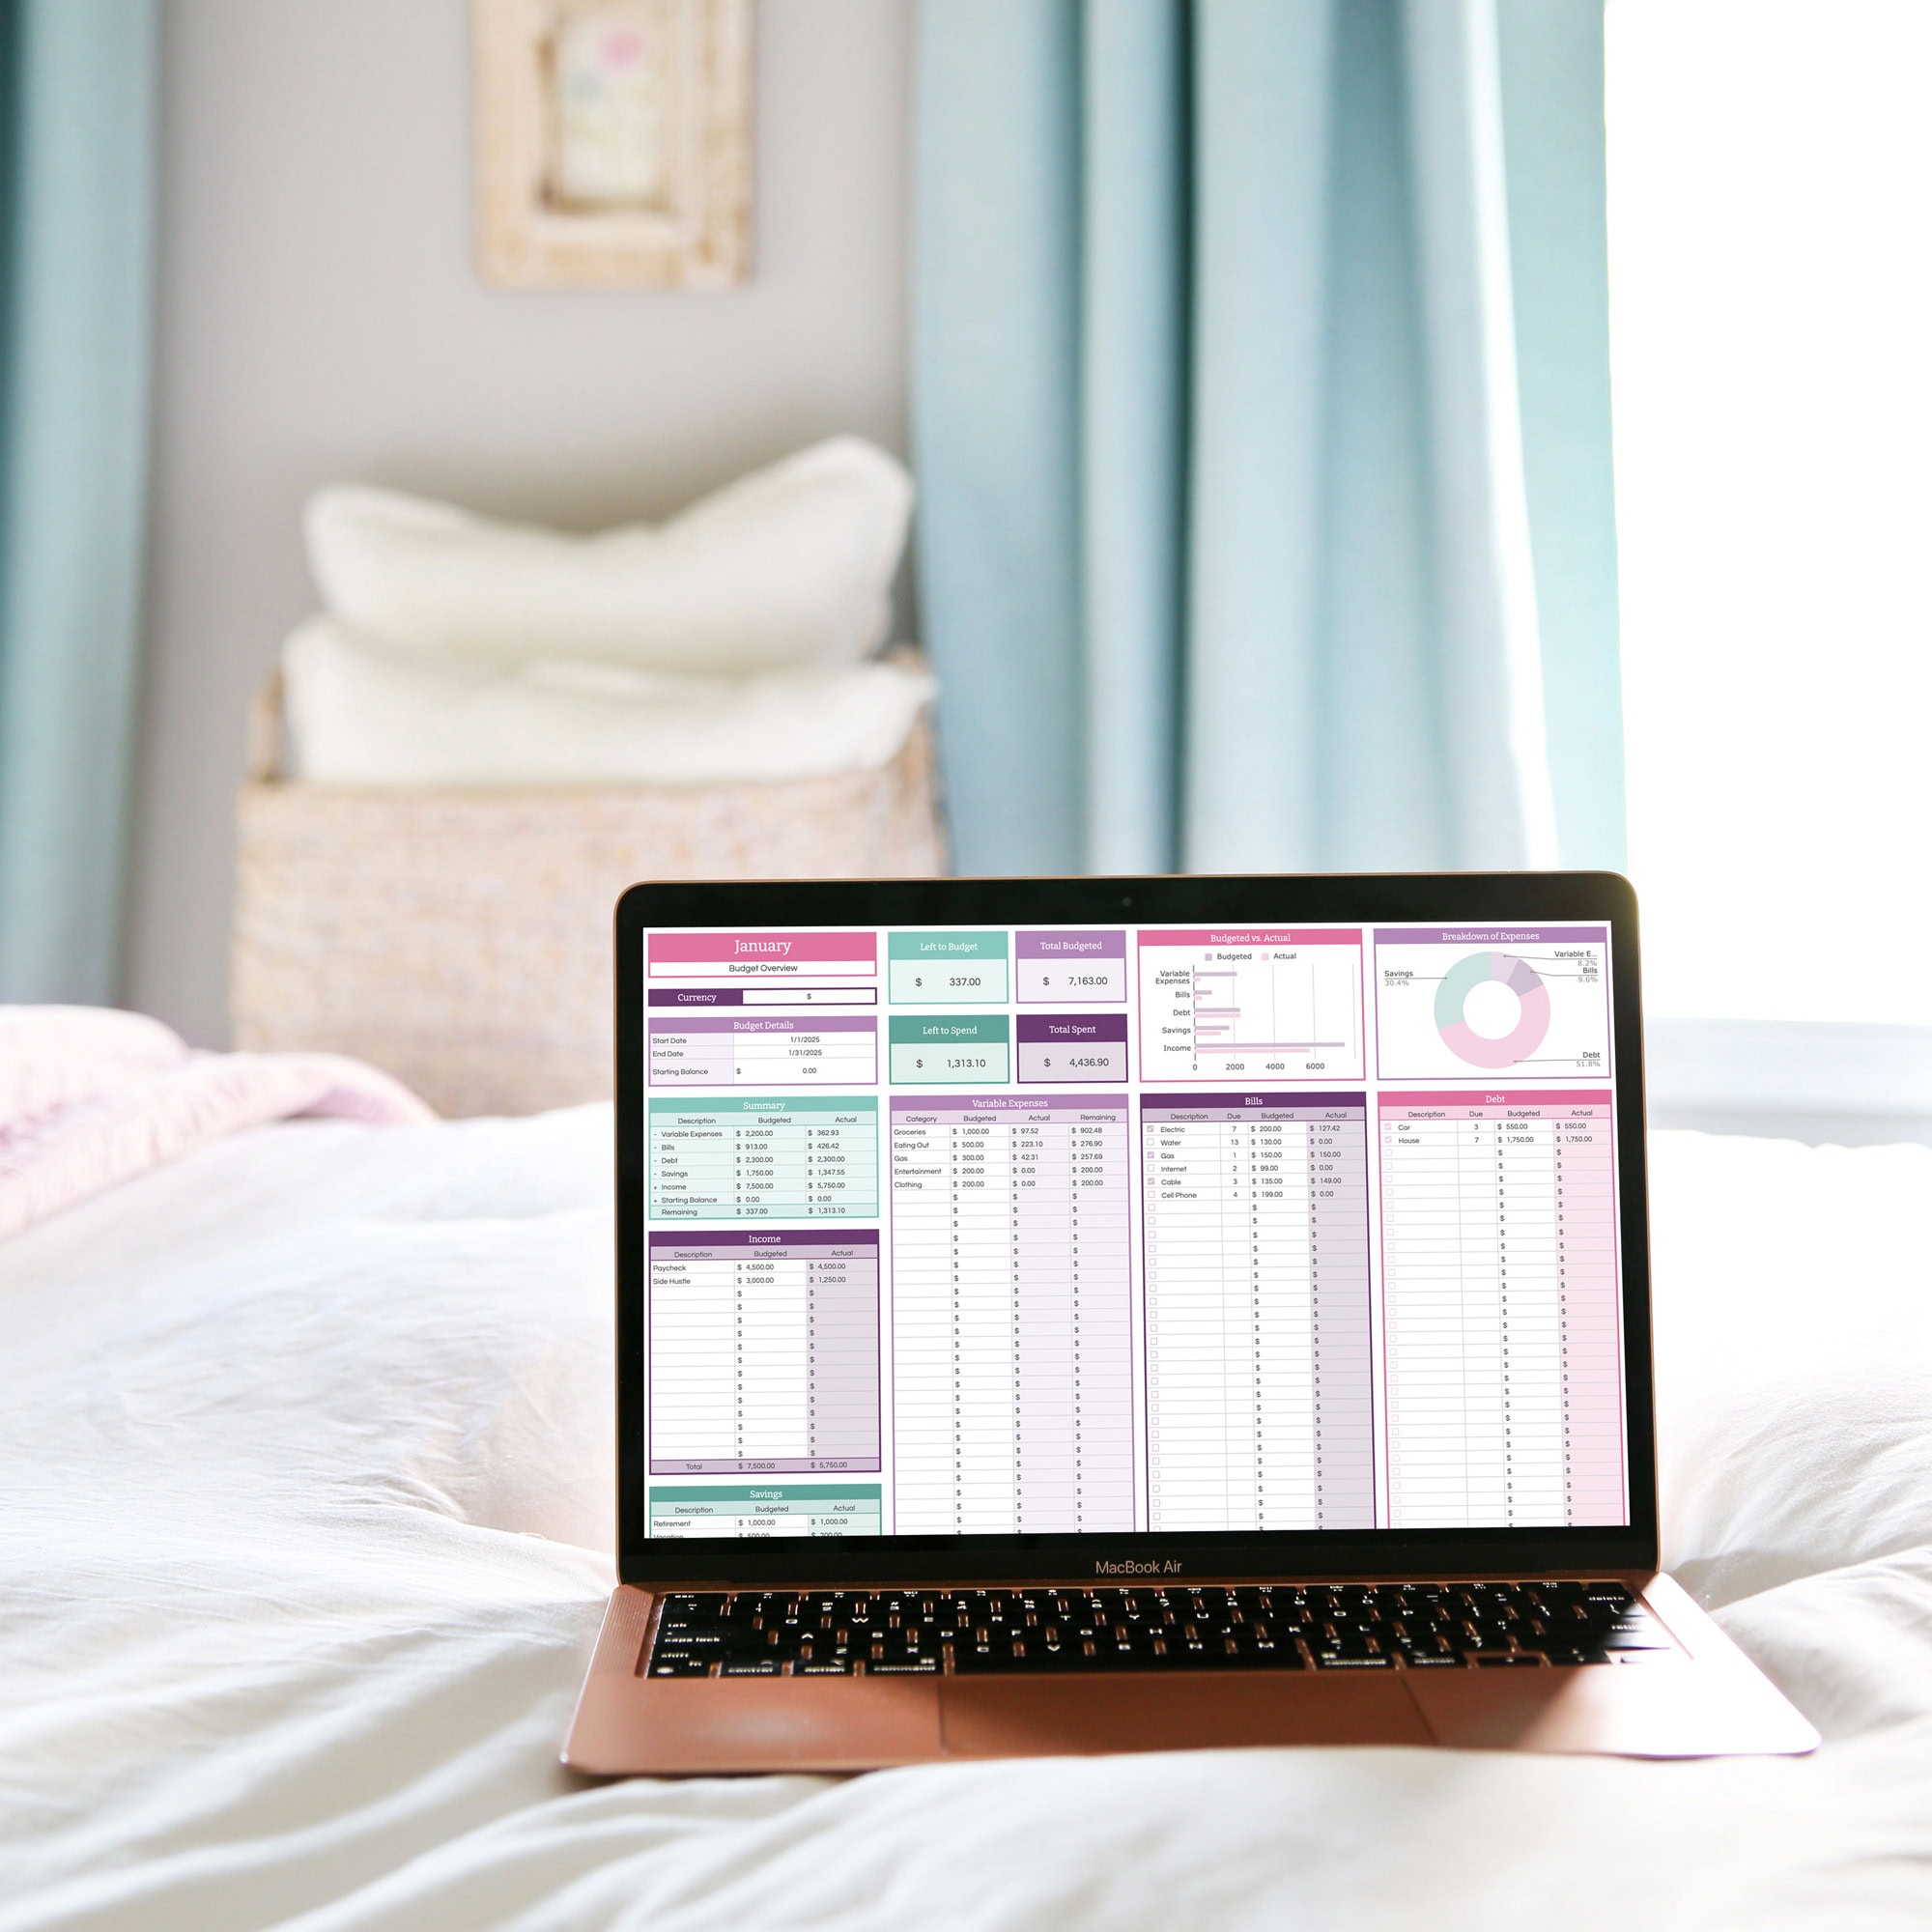
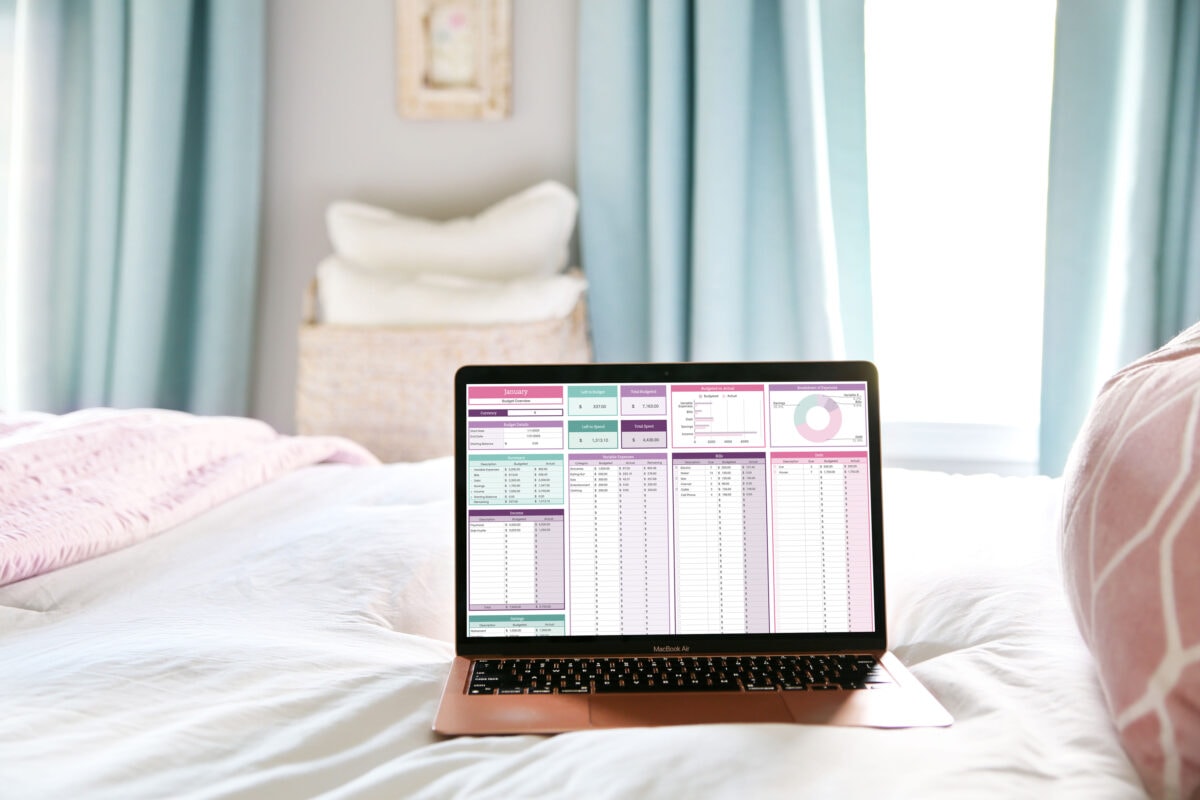
The next chronological step in taming an irregular income is establishing a conservative financial baseline. Seasoned budgeters advise looking backward at the past 12 months of earnings to identify the lowest-grossing months. By deliberately structuring the monthly baseline budget around a lower-income month rather than a peak or average month, families ensure that their core spending targets remain entirely achievable, even during a business slump.
Phase 3: Building the Financial Cushion
Once the baseline is established, the timeline shifts toward fortifying safety nets. Setting up automated transfers into an emergency or buffer fund during high-earning periods removes the temptation to spend excess cash. Over time, as savings accumulate from a modest $1,000 starter fund to three, six, or even twelve months of essential living expenses, the anxiety of income fluctuation begins to dissipate entirely.
Supporting Data and Core Strategies
Creating a functional budget on a variable income requires specific, actionable methodologies. Financial coaches recommend four foundational pillars to keep household finances on track:
1. Base Your Lifestyle on a Conservative Income Month
When making major long-term financial commitments—such as determining an affordable housing payment, financing a vehicle, or committing to recurring monthly subscriptions—households must base their calculations on a lower-income month. Designing a lifestyle around peak earning months is a primary driver of financial distress. By keeping expectations modest, families protect themselves against unexpected economic downturns.

2. Prioritize a Robust Buffer and Emergency Fund
Because fluctuations are guaranteed, an emergency fund acts as the shock absorber for household finances. To overcome the psychological resistance of manually moving money into savings (where people often rationalize leaving extra cash in their primary checking accounts), experts strongly recommend setting up automated weekly transfers.
- Level 1: Save an initial $1,000 safety net.
- Level 2: Build up to one month’s worth of essential expenses.
- Level 3: Expand the fund to cover 3 to 6 months—or up to a full year—of core living costs, depending on individual income volatility.
3. Implement an Ordered Priority List for High-Income Months
Surplus revenue months are a welcome relief, but without a plan, extra cash tends to vanish on impulse purchases. Successful households maintain a pre-approved, ordered list of financial priorities to tackle when earnings exceed the baseline budget. This hierarchy often includes:
- Padding the emergency buffer fund.
- Aggressively paying down high-interest debt.
- Saving for anticipated large future expenses (such as annual insurance premiums, property taxes, vehicle replacements, or holiday spending).
- Funding predictable seasonal costs, like children’s sports leagues, summer camps, or tuition.
- Accelerating long-term investments, including maxing out retirement accounts or contributing to college savings plans.
Note on Discretionary Spending: Effective budgeting does not mean a life of total deprivation. Incorporating dedicated, modest categories for hobbies and entertainment prevents "budget fatigue," ensuring that individuals do not rebel against overly restrictive constraints and accidentally overspend.

4. Treat Your Budget as a Living, Breathing Document
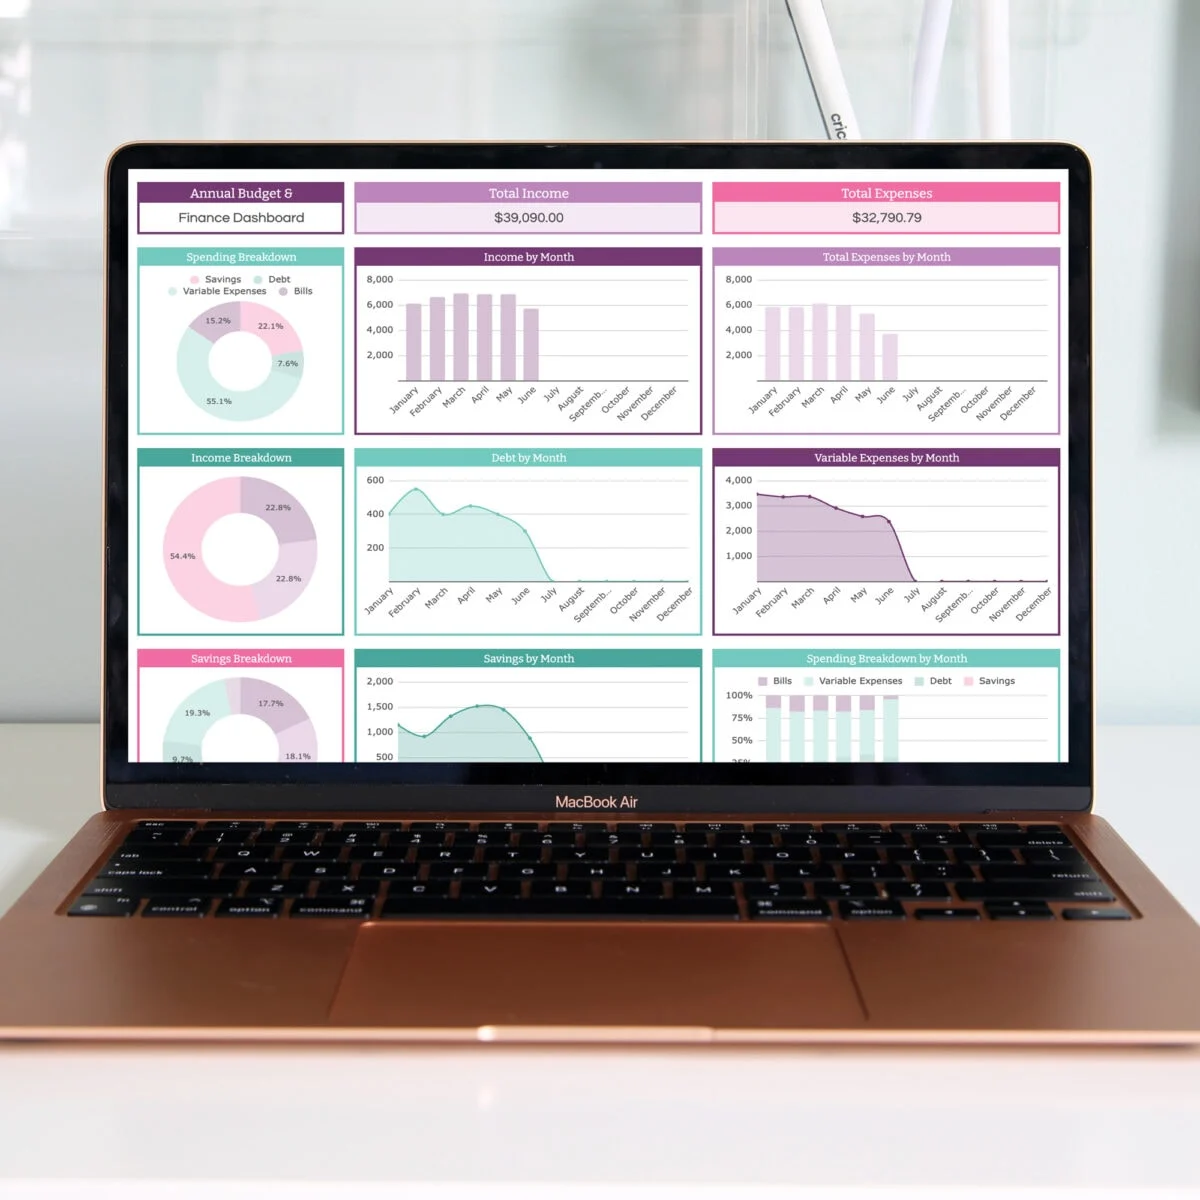
A budget is never truly set in stone. As months pass and spending patterns emerge, families must continuously evaluate their data. If a particular expense category consistently runs under budget, those funds can be reallocated elsewhere. Conversely, if a category continually runs over budget, adjusting the allotment to a realistic figure eliminates unnecessary monthly frustration.
Official Responses and Expert Perspectives
Financial advisors and consumer advocates widely endorse proactive tracking as the most effective antidote to financial anxiety. While personal finance philosophies vary regarding debt repayment methods and investment vehicles, there is a unified consensus on the necessity of cash-flow visibility.
According to consumer credit counselors, individuals struggling to make ends meet on a variable income have two ultimate levers to pull: cutting fixed and variable expenses or actively working to increase top-line revenue through side hustles, freelance expansions, or contract renegotiations. When budgets are actively tracked, they provide the empirical data necessary to make these difficult structural decisions before a financial emergency forces a crisis response.

Furthermore, behavioral economists note that the simple act of tracking expenditures triggers a psychological mindfulness that naturally curbs impulse buying. When individuals are forced to log transactions and categorize their spending, they become inherently more selective about where their hard-earned money goes.
Implications: Reclaiming Control and Moving Forward
The broader implications of mastering an irregular income extend far beyond simple mathematical balancing. For millions of self-employed individuals and independent contractors, the psychological shift from financial passivity to active stewardship is transformative.
When people break free from the fear of the unknown, budgeting ceases to feel like a restrictive punishment. Instead, it evolves into an empowering tool that grants absolute clarity over what a household can comfortably afford, where adjustments can be made, and how long-term goals can be steadily achieved.
By replacing guesswork with intentional strategy, irregular income earners can secure their financial futures, mitigate daily stress, and build lasting wealth—proving that financial peace of mind is entirely attainable, regardless of how unpredictable the next paycheck might look.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute personalized financial, legal, or professional advice. Readers should consult with a certified financial planner or professional advisor before making major financial decisions.