WASHINGTON — In an era where traditional school curricula routinely overlook practical personal finance, a growing movement of parents is finding unconventional classrooms for their children. The latest trend gaining traction among financially savvy households transforms the annual summer trip from a financial black box into a hands-on laboratory for budgeting, expense tracking, and long-term economic stewardship.
By deputizing their children as chief financial officers of family getaways, parents are demystifying the mechanics of money management. What starts as a simple spreadsheet exercise is rapidly evolving into a blueprint for how modern families can close the generational gap in financial education—proving that learning how to manage capital doesn’t have to be a source of stress, but can instead be an engaging, empowering family activity.
The Core Philosophy: Bridging the Financial Literacy Gap
Despite spending thousands of hours in formal classrooms, young adults frequently enter the independent workforce lacking basic money management skills. Concepts such as compound interest, cash-flow budgeting, and opportunity cost are rarely prioritized in standard high school curricula. Recognizing this deficiency, parents are increasingly taking financial education into their own hands.
The primary objective is simple yet profound: to instill financial confidence before children leave the safety of the family home. By introducing incremental financial responsibilities over time, parents aim to normalize monetary stewardship. Instead of treating money as a taboo subject or a source of anxiety, this proactive approach reframes budgeting as a proactive tool for achieving personal goals, regardless of income level.
Vacations offer an ideal sandbox for these lessons. Unlike day-to-day household expenses—which are often abstract and recurring—a vacation has a hard start, a definitive end, and a contained set of financial parameters. This makes it the perfect environment for accelerated financial comprehension.
Chronology of a Trip: From Sinking Funds to Spreadsheet Management
The journey toward financial literacy on the road actually begins months before the first suitcase is packed. The process follows a structured, chronological path designed to teach children that financial freedom is the result of deliberate planning rather than impulse borrowing.
Phase 1: Year-Round Preparation and Sinking Funds
Long before departure day, families utilize what financial planners call "sinking funds." Rather than financing a getaway through high-interest credit cards or loans, money is systematically set aside week by week over the course of the year. This establishes the first crucial lesson: the discipline of delayed gratification. When vacation season arrives, the trip is fully funded, and the family operates with a precise, uncompromised spending ceiling.
Phase 2: Budget Structuring and Categorization
Prior to departure, parents establish baseline spending categories. While these can vary depending on the destination, standard allocations typically include:

- Lodging and accommodations
- Transportation (flights, fuel, public transit)
- Dining and groceries
- Excursions and entertainment
- Miscellaneous spending and souvenirs
Once these initial parameters and numerical caps are established by the adults, the administrative reins are handed directly to the children.
Phase 3: Real-Time Execution on the Road
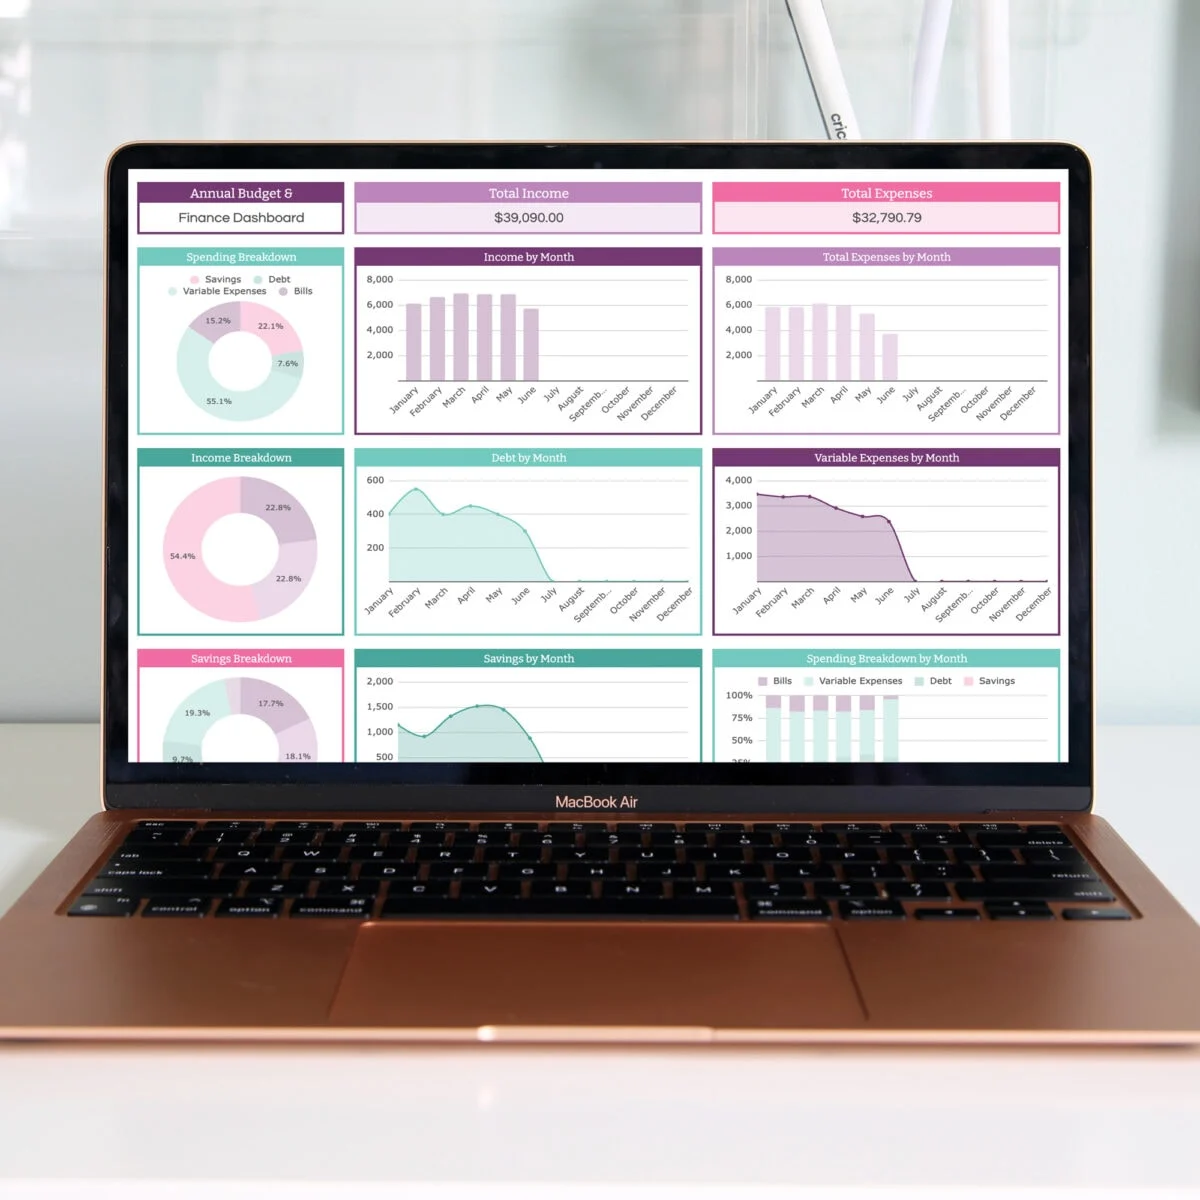
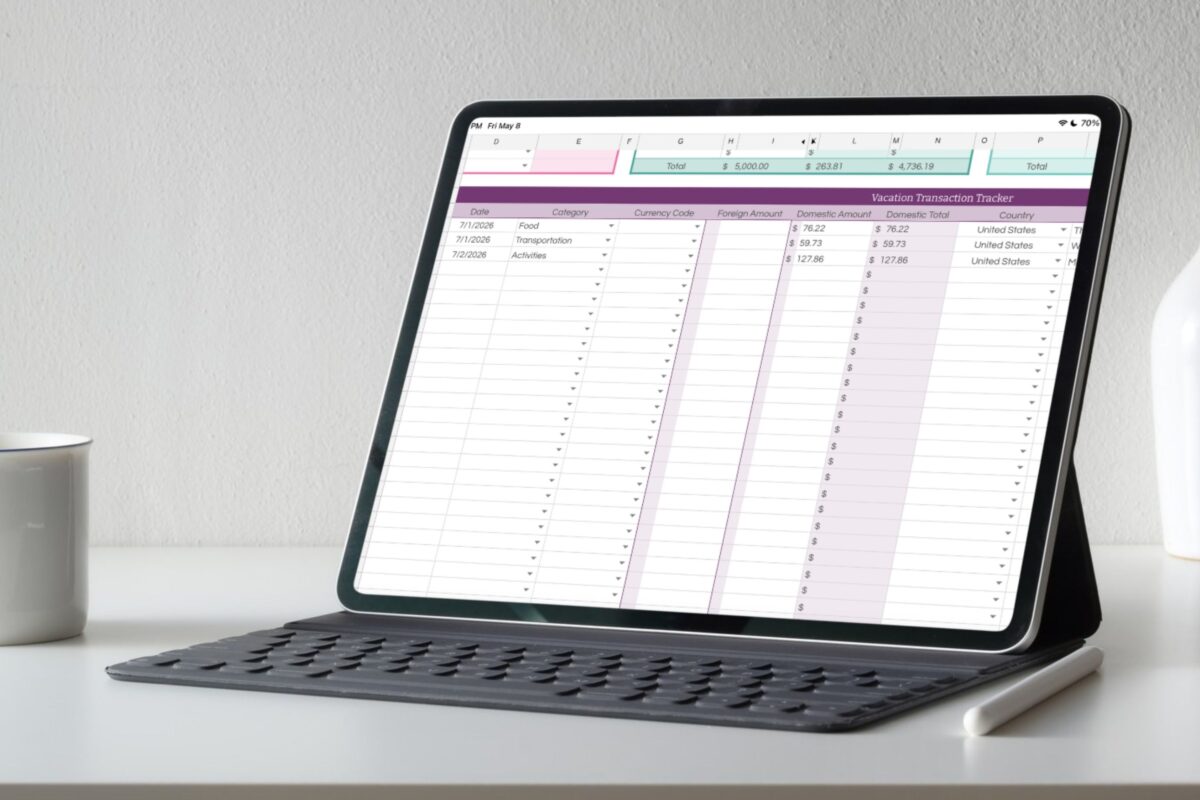
Once traveling begins, every single transaction becomes an educational opportunity. Using shared cloud-based tools—such as a mobile-accessible Google Sheets travel planner—children take turns logging every purchase as it happens. Because modern digital spreadsheets automatically calculate remaining balances, children quickly learn to monitor their remaining margins and project daily spending limits.
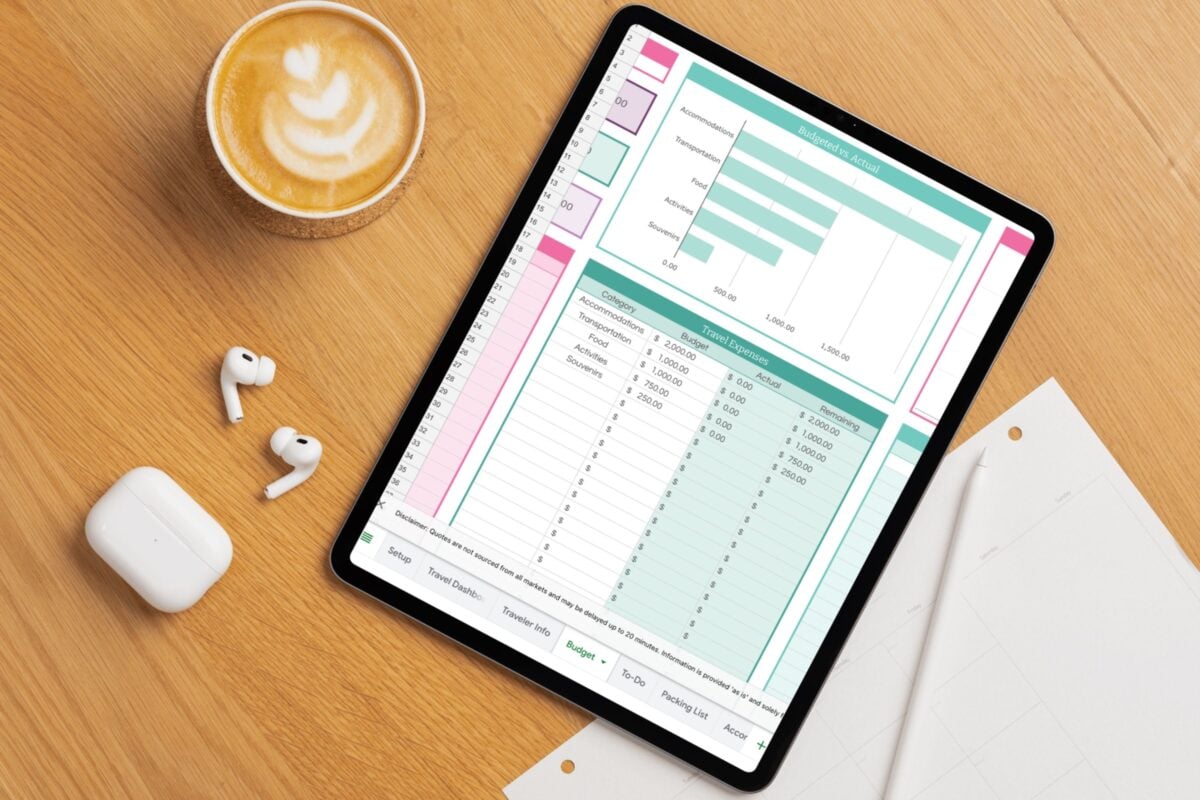
As the trip progresses and the remaining funds shrink, the dynamic shifts. Children naturally transition from passive observers to active financial monitors, frequently evaluating whether prospective purchases align with the family’s broader financial targets.
Supporting Data and Educational Methodology
Financial educators and behavioral economists have long championed experiential learning over theoretical instruction. According to recent youth financial literacy studies, children who participate directly in household budgeting exercises demonstrate a 40% higher retention of core economic concepts compared to peers who only receive verbal instruction.
| Traditional Financial Education | Experiential Vacation Budgeting |
|---|---|
| Abstract classroom lectures on saving | Real-time tracking of finite resources via digital spreadsheets |
| Hypothetical scenarios and worksheets | Tangible consequences (e.g., evaluating souvenir vs. excursion costs) |
| Money as a source of parental stress | Budgeting framed as a game-like strategy for achieving goals |
| Isolated learning | Collaborative family problem-solving and resource allocation |
The integration of technology plays a pivotal role in this dynamic. By utilizing mobile apps and cloud spreadsheets, younger generations—who are digital natives—engage with personal finance software in a format that feels intuitive and modern. This eliminates the friction traditionally associated with ledger-based budgeting.
Expert Perspectives and Parental Insights
Child development specialists and family finance advocates praise the method for its psychological framing. By shifting the perspective of a budget from a punitive restriction to a strategic advantage, children learn to view financial boundaries as protective rather than limiting.
"When kids see that money is finite, but that managing it can be a collaborative puzzle rather than a source of panic, their entire relationship with money changes," notes one family finance strategist. "They stop asking, ‘Can we afford this?’ and start calculating, ‘How does this choice impact our remaining goals?’"
Anecdotal evidence from parents who implement this system highlights the unexpected behavioral shifts in children. Beyond simply logging numbers, children develop a keen eye for value. Stories of children playfully holding parents accountable for seemingly overpriced roadside purchases illustrate how deeply the lessons resonate. These lighthearted interactions foster an environment where financial consciousness is normalized and discussed openly without shame or fear.
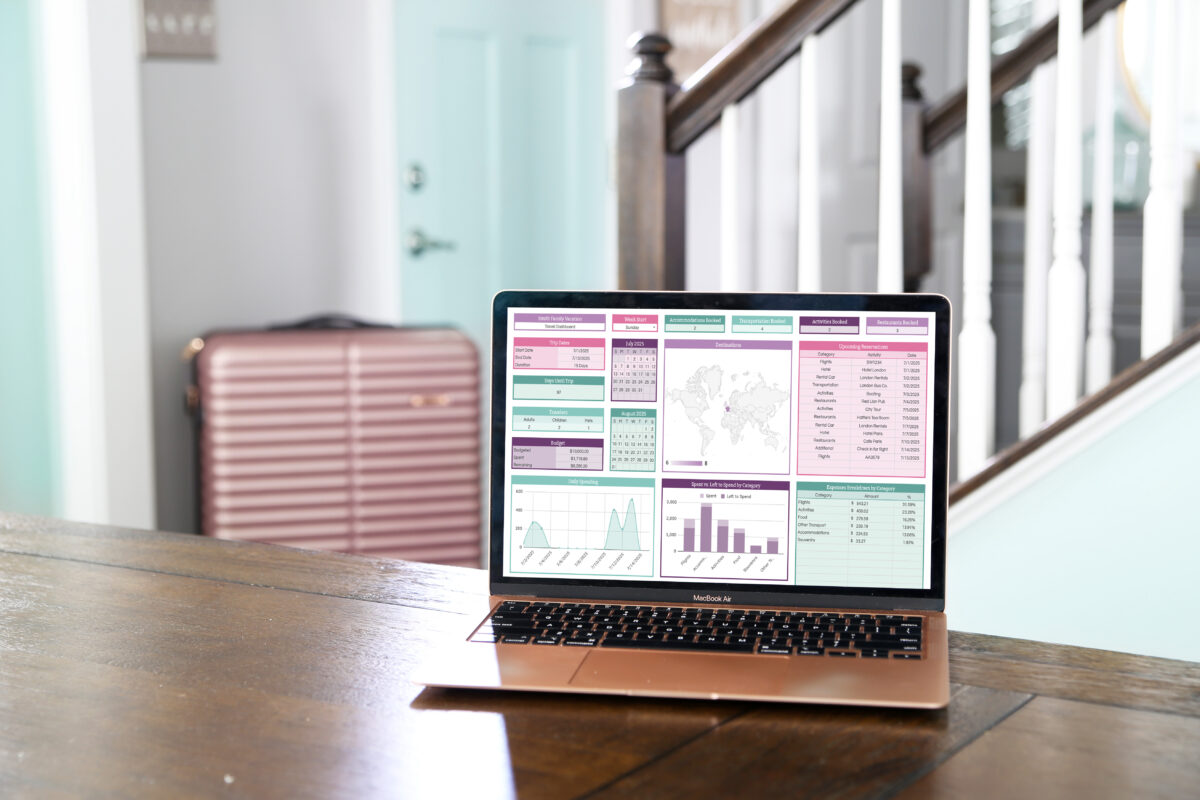
Furthermore, when unexpected expenses inevitably arise—a delayed flight, a higher-than-expected meal cost—parents and children collaborate to reallocate funds from one category to another. This teaches the real-world concept of financial agility: the understanding that a budget is not a rigid cage, but a flexible tool that can be adjusted to meet changing priorities.
Implications for the Future Financial Landscape
The long-term implications of embedding financial literacy into family travel are significant. As these children transition into young adulthood, the habits formed over vacation spreadsheets translate directly into college budgeting, initial car purchases, and eventual homeownership.
Key Long-Term Takeaways:
- Debt Avoidance: By witnessing the power of sinking funds firsthand, children are less likely to rely on consumer debt to fund lifestyle experiences.
- Critical Decision-Making: Learning to say "no" to minor, impulsive desires in favor of major, high-value experiences trains the brain for long-term wealth building.
- Technological Fluency: Early mastery of digital budgeting tools ensures that managing personal cash flow in adulthood feels like second nature.
- Emotional Resilience: Viewing financial adjustments as creative problem-solving rather than crises reduces lifelong financial anxiety.
Ultimately, turning a family vacation into a financial workshop does more than just balance a ledger for a week; it equips the next generation with the competence, confidence, and clarity required to navigate an increasingly complex economic world. By making financial responsibility a shared, enjoyable family adventure, parents are laying the groundwork for a secure and thriving financial future.