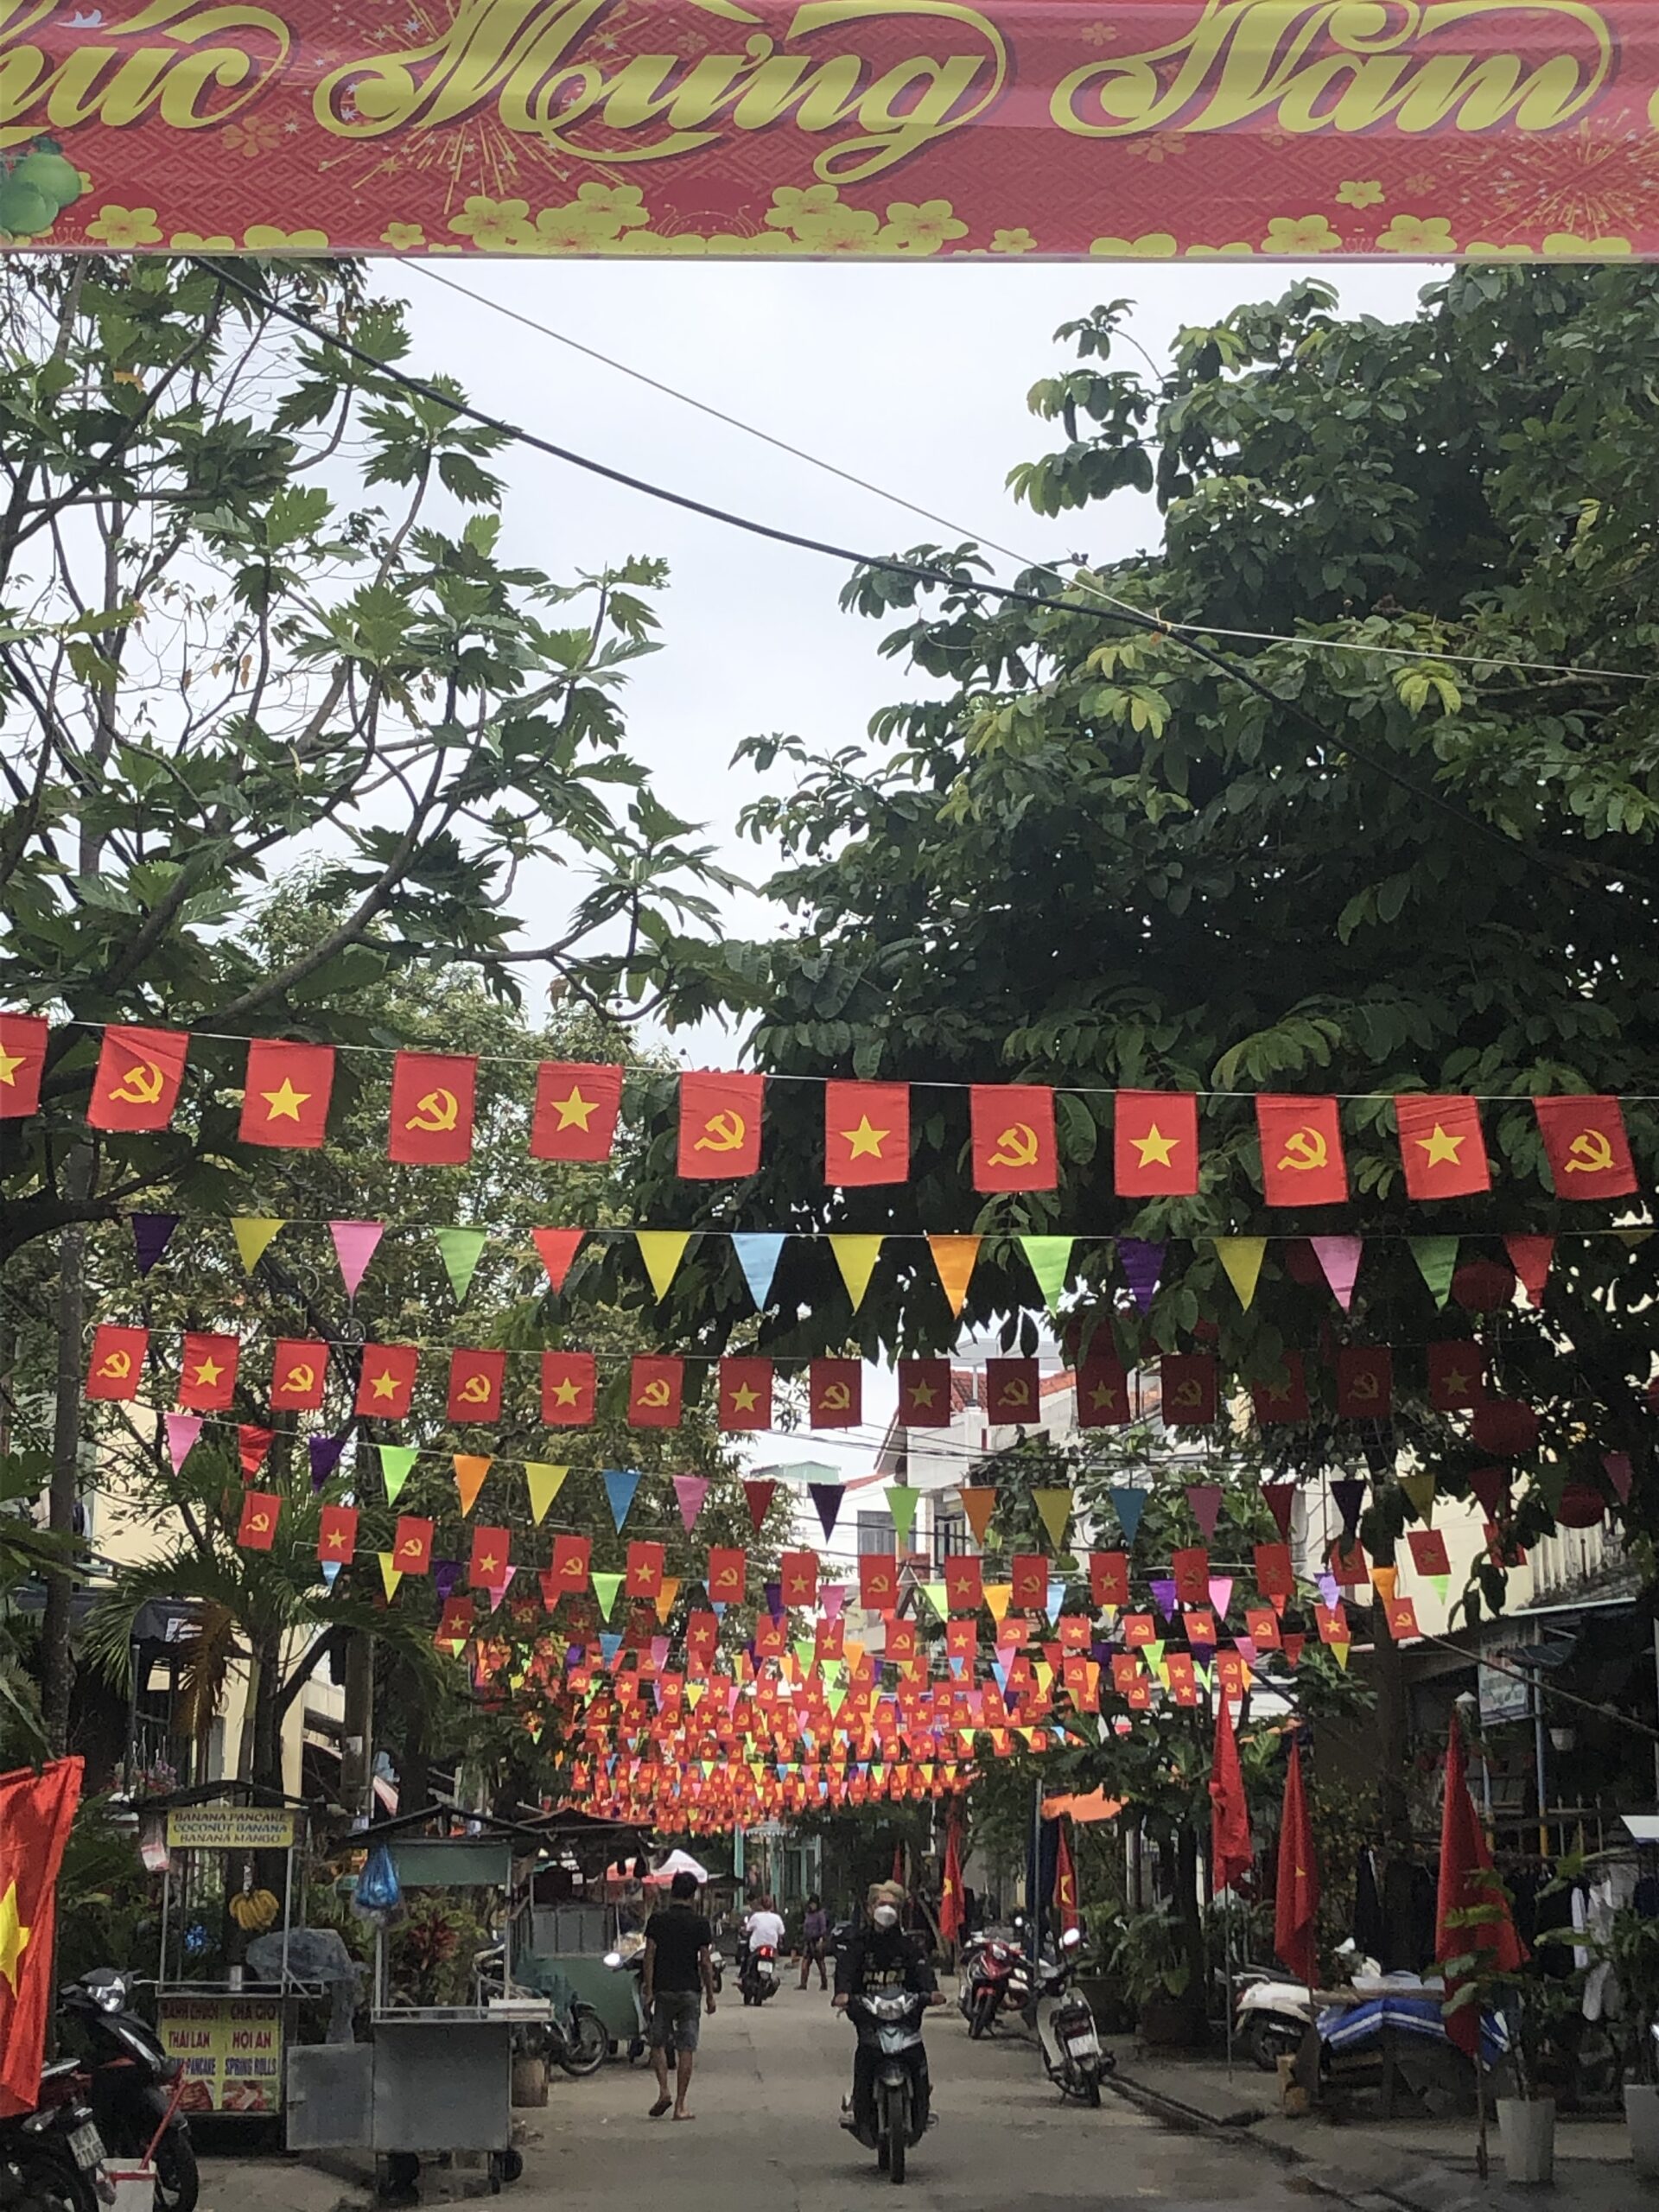
For many, the expatriate experience represents the pinnacle of personal and professional freedom—an opportunity to immerse oneself in new cultures, expand global perspectives, and often, to benefit from a significantly lower cost of living. However, behind the picturesque photos of bustling night markets and serene temple visits lies a complex reality: the need to maintain long-term financial health while navigating the uncertainty of an eventual return home.

Laura, 32, and her husband Ethan, 38, find themselves at this exact juncture. Currently living in Hanoi, Vietnam, the couple has spent the last two years building a life abroad. While they have enjoyed the freedom of their expat lifestyle, they are now grappling with the looming question of how to successfully transition back to the United States without derailing their financial future.
The Core Dilemma: Balancing Wanderlust with Security
Laura and Ethan’s story is one of rapid progress followed by a period of intentional "holding." Originally from Philadelphia, Pennsylvania, the couple moved to Vietnam to accommodate Ethan’s career as an international school teacher. For Laura, the move provided the space to pivot from a career in software engineering—a path she pursued after a company-sponsored coding bootcamp—to her true passion: public health. She is currently completing her Master’s degree in Public Health (MPH) with a focus on maternal and child health.

Despite their successful debt-repayment journey—having cleared a combined $140,000 in student loans in less than five years—Laura admits to a lingering sense of financial anxiety. This concern is rooted in a desire to return to the U.S. in the coming years to settle down, buy a home, and start a family. The prospect of re-entering the high-cost American housing market, coupled with a two-year hiatus from retirement contributions, has left her seeking a roadmap for stability.

Chronology: From Debt Repayment to International Life
The couple’s financial trajectory has been defined by extreme focus and discipline:

- Pre-2021: Both individuals aggressively attacked their student debt. Ethan cleared $80,000 in loans within four months of meeting Laura, while she successfully paid off $60,000 in 11 months.
- 2021: The couple relocated to Hanoi. Ethan accepted an international teaching role that includes an expat package covering rent and annual flights home.
- 2022–2023: Laura left her local job to pursue her MPH full-time. The couple utilized this period to travel extensively across Southeast Asia and East Asia, leveraging the flexibility of Ethan’s teaching schedule.
- Present Day: The couple is preparing for a transition. Laura is nearing the completion of her degree, and they are beginning to map out the financial logistics of repatriating to the U.S.
Supporting Data: A Snapshot of Financial Standing
Laura and Ethan’s financial profile is characterized by high liquidity and a total absence of consumer debt, though they remain uncertain about the optimization of their assets.

Asset Summary (Total: ~$235,708):

- Cash Reserves: Approximately $104,370, held across high-yield savings and checking accounts.
- Retirement Accounts: $112,555 across multiple 401k, 403b, and IRA accounts.
- Investment Portfolios: $18,783 in a taxable brokerage account.
Monthly Expenses:

- Living in Vietnam, their monthly expenses hover around $1,741. This includes everything from groceries and utilities to gym memberships and international travel. The lack of rent payments, which are covered by Ethan’s employer, is a significant factor in their ability to save.
Expert Analysis and Official Considerations
In a collaborative effort to address their concerns, financial experts and community observers have weighed in on their strategy, focusing on three critical pillars: housing, retirement, and investment optimization.

The Myth of the Cash Home Purchase
One of the most pressing questions from Laura was whether it is "terrible" to buy a house in cash upon returning to the U.S. The consensus among financial experts is that while paying cash provides a sense of psychological security, it is often a sub-optimal financial decision.

"When you buy a house in cash, you are missing out on the opportunity cost of that capital," explains the advisory consensus. By keeping such a massive sum in a non-invested state, the couple loses the potential for market growth. Historically, stock market returns have significantly outperformed mortgage interest rates. Furthermore, a home is an illiquid asset; once the money is in the walls of the house, it is difficult to access in the event of an emergency.

Retirement Contributions for Expats
The couple’s anxiety regarding their two-year break from retirement savings is common among expats. The ability to contribute to an IRA while living abroad is contingent upon the taxpayer’s specific tax filing status, particularly how they utilize the Foreign Earned Income Exclusion (FEIE).

If a taxpayer excludes all of their income, they may not have the "earned income" required to contribute to an IRA. However, by using the Foreign Tax Credit (FTC) instead of the FEIE, or by qualifying for a Spousal IRA, many expats can continue to fund their retirement accounts. It is strongly recommended that the couple consult with an expat-specialized tax professional to audit their specific tax filings.

Optimizing Investment Vehicles
A recurring issue in the couple’s profile is the fragmentation of their retirement accounts. With multiple 401k and 403b plans from previous employers, the couple is advised to perform a rollover into a unified IRA. This move grants them full control over their investment choices, allowing them to move away from potentially high-fee, employer-managed funds and into low-cost, total-market index funds.

Implications for the Future
As Laura and Ethan look toward the next decade, their goals are clear: financial stability, homeownership, and the start of a family. The path forward requires a shift from a "survival/repayment" mindset to a "wealth-building" strategy.

- Stop Hoarding Cash: While their current cash reserve of over $100,000 is excellent for short-term flexibility, it should not be viewed as a permanent home for their wealth. Once they establish a new baseline in the U.S., a significant portion of this should be redeployed into diversified investments.
- Understand the Pension System: For Ethan, the PA Teachers pension (PSERS) is a significant, yet poorly understood asset. Clarifying his eligibility and the potential impact on future Social Security benefits is a high-priority task.
- The "Automation" Strategy: To mitigate Laura’s anxiety, the recommendation is to shift toward an automated system once they are back on a stable, domestic income. By setting up auto-transfers to retirement accounts and index funds, the couple can remove the emotional labor from their finances, allowing the "set-it-and-forget-it" mechanism of compound interest to work in their favor.
Conclusion
Laura and Ethan represent a generation of professionals who are redefining the traditional career path. Their experience in Vietnam has been a masterclass in frugal living and intentional spending. While the uncertainty of their next chapter is causing legitimate stress, their foundational habits—zero debt and a high savings rate—provide a robust safety net. By reframing their view on homeownership and tightening their investment strategy, they are well-positioned to turn their international adventure into a springboard for long-term American prosperity.