For many, the transition into their mid-30s is defined by a quest for security, property ownership, and the solidification of long-term financial health. For Brian and Michael, a couple based in central Connecticut, this period has been marked by professional growth, the joys of home life with their two cats, and the sobering reality of lingering debt. As they approach their 10-year anniversary, the duo finds themselves at a crossroads: while they have achieved significant career success, they feel hindered by a cycle of consumer debt and a lack of real estate equity.
Seeking to move beyond the “next level of adulting,” the couple recently submitted their financial profile to the Frugalwoods Reader Case Study series. This initiative serves as a public forum where individuals share their financial dilemmas to receive expert analysis and community-driven feedback.

The Human Context: Who Are Brian and Michael?
At 34, Brian and Michael have built lives centered on public service and professional advocacy. Michael serves as a project coordinator for a state behavioral health agency and supplements his income as a disability leadership coordinator. His work is deeply personal, stemming from his own journey as a brain injury survivor. Brian, meanwhile, leverages his experience as a quality assurance manager for a state-run hospital.
Their lives are filled with intellectual and creative pursuits: Michael enjoys literature, drawing, and culinary arts, while Brian is a dedicated outdoorsman, hiker, and lifelong learner. Despite their professional accomplishments, both men express a sense of lingering "financial shame." They worry they are falling behind their peers, particularly regarding home ownership, retirement planning, and the discipline required to maintain a permanent state of debt-free living.
Chronology of Financial Strain
The couple’s current urgency stems from a tumultuous 2022 and 2023. Their financial trajectory was disrupted by two major life events that shifted their timeline for home ownership.
- The Transition: After eight years in a cozy, affordable 600-square-foot studio apartment, the couple was forced into the volatile 2022/2023 housing market. The process of finding a new home, combined with unexpected veterinary expenses for their two new kittens, created a significant drain on their liquid savings.
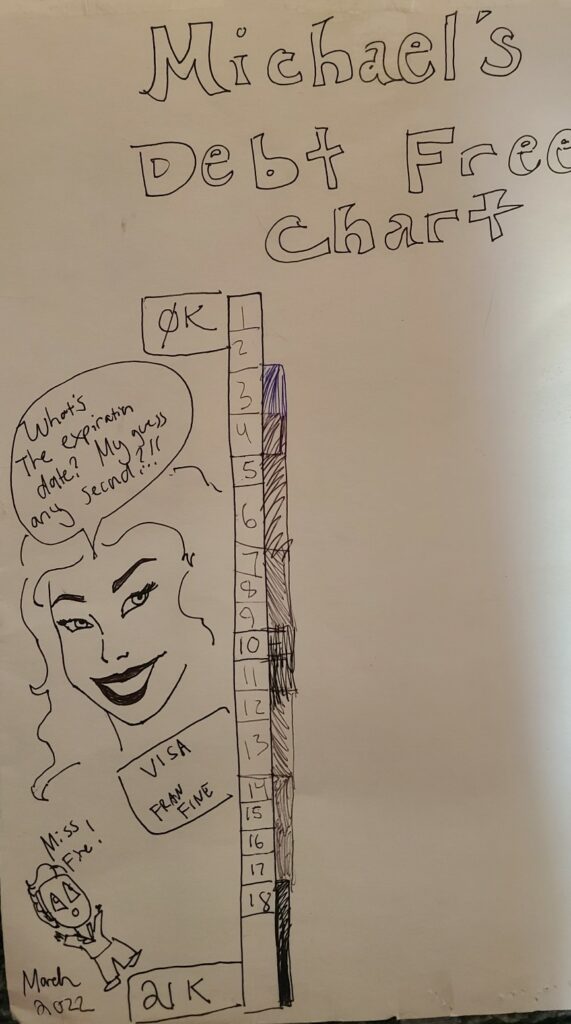
- The Debt Realization: While Brian successfully paid off $58,000 in student loans several years ago, the couple currently faces approximately $28,259 in consumer debt. Brian, despite his recent career success, carries the weight of this debt and a lack of diverse, long-term investments.
- The Current State: They have successfully navigated the move into a spacious, industrial-style apartment in a refurbished mill. While the space is a massive upgrade—complete with a home library and dedicated office—it has highlighted their lack of "land to call their own," fueling a desire to re-enter the housing market as soon as possible.
Financial Snapshot: Income, Debt, and Assets
A breakdown of their finances reveals a household with significant earning power, yet one currently hampered by high monthly overhead.
Income and Expenses
The couple reports a combined gross annual income of $167,544, resulting in a net income of approximately $109,455. Their monthly expenses, however, total $8,035. This leaves a razor-thin margin for error. Major line items include:
- Rent: $2,000
- Debt Payments: $2,000 (combined)
- Transportation (Car repairs, gas, transit): $1,064
- Pet Care: $517
Debt Breakdown
The couple is currently managing three primary credit card debts:
- Brian’s Visa (SCU): $16,057 (0% interest until Nov 2023, then 17.99%)
- Michael’s Visa Platinum: $9,700 (10.99%)
- Brian’s Visa Platinum (Navy Federal): $2,503 (0.99% until Nov 2023, then 17.74%)
Assets
Their total asset portfolio stands at $91,250. This includes various retirement vehicles such as a 401k, 403b, 457, and a pension. However, the couple feels their investments are underfunded, particularly given their concerns regarding the future of Social Security and the rising cost of living.
Professional Analysis and Recommendations
In her analysis, Liz Frugalwoods highlights that Brian and Michael are in a stronger position than they believe. She notes that their "spreadsheet problems" are solvable, provided they pivot from their current reactive stance to a proactive, structured financial strategy.
1. The Power of Expense Tracking
The most immediate recommendation is the implementation of rigorous expense tracking. With a net income of over $109,000 and annual spending of $96,414, the couple has a potential surplus of over $13,000 per year. Liz emphasizes that they must identify exactly where this money is going. Using tools like Empower (formerly Personal Capital) or simple manual spreadsheets is essential to transition from "famine and feast" cycles to stability.
2. Debt Elimination as a Priority
The strategy proposed involves an immediate "spending detox." By cutting discretionary items—such as dining out, non-essential home goods, and extraneous subscriptions—the couple could theoretically free up an additional $1,370 per month. By channeling this into their existing debt-payoff plan, the couple could feasibly be completely consumer-debt-free within roughly 6.5 months.
3. Redefining the Emergency Fund
The couple currently holds $9,000 in cash, which covers roughly one month of expenses. Liz argues that this is inadequate. Once the consumer debt is retired, the priority must shift to building a robust emergency fund—a buffer designed for the "predictable unpredictability" of life, such as future car repairs or household emergencies.
4. Retirement Strategy
Brian and Michael have access to the "triple crown" of retirement: a 403b, a 457, and a pension. Liz recommends that they prioritize increasing contributions to their workplace accounts before focusing on a home downpayment. The 457b, in particular, offers unique advantages for those who may wish to retire before the age of 59.5.
5. Education: The "Master’s Degree" Caveat
Addressing Michael’s question regarding a potential graduate degree for Brian, the advice is blunt: do not pursue further education unless it is tied to a guaranteed, significant salary increase. In their current state of debt, the cost of time and tuition is a luxury they cannot afford.
Implications for Long-Term Goals
The ultimate takeaway for the couple is that their desire for home ownership is a valid long-term goal, but it must be deferred until their financial foundation is secure.
The Priority Order of Operations:
- Debt Repayment: Eliminate all consumer debt using a snowball or avalanche method.
- Emergency Fund: Build 3–6 months of living expenses in a high-yield savings account.
- Retirement Optimization: Maximize tax-advantaged accounts to leverage compound interest.
- Real Estate: Begin saving for a downpayment only after the above steps are firmly established.
By shifting their perspective from "shame" to "strategy," Brian and Michael can move past the recurring cycle of debt. The goal is to reach a "comfortable middle"—a state of financial homeostasis where their lifestyle is supported by their income, and their long-term security is guaranteed by their current, disciplined choices.
A Call for Community Input
As is tradition with Frugalwoods case studies, the readers have been invited to weigh in with their own insights. The case of Brian and Michael resonates with many young professionals who feel the pressure of the modern economy. By opening their books to public scrutiny, they are taking the most difficult step in financial planning: the move from silence to transparency. With a clear plan, the right priorities, and a commitment to living within their means, the goal of home ownership and total financial independence is not only possible—it is well within their reach.